Insurance Litigation 2026
USA – Maryland
Trends and Developments
Authors
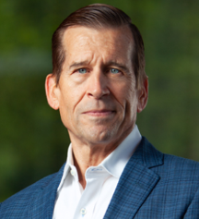
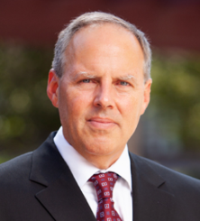
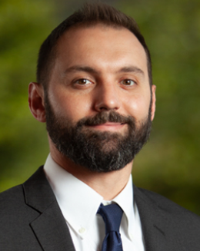
Funk & Bolton, P.A. offers client services across the spectrum of insurance regulation, insurance litigation, legislative services, and creditors’ rights. The insurance group offers a unique perspective on Maryland insurance law, pairing legislative, regulatory, and litigation expertise inside a boutique law firm with offices in Baltimore and Annapolis. Maryland insurers engage the firm to perform regulatory, compliance, and litigation work in Maryland and beyond, while national insurers engage the firm for its Maryland insurance expertise. The firm provides guidance to insurance entities from concept through formation, incorporation, and licensure, including form and rate filings. The firm supports insurers in market conduct and financial examinations, regulatory proceedings, consumer complaints, holding company act issues, boards and committees. The firm represents insurers in litigation in administrative proceedings, and state and federal court. The firm regularly handles M&A transactions and complex restructurings, including reinsurance transactions. The firm is regularly engaged to serve as litigation counsel for national and international insurers on important questions of Maryland law.
Maryland’s regulatory and administrative environment makes insurance litigation in Maryland different from most states. This is in part because the Maryland Insurance Commissioner (the “Insurance Commissioner”) is charged with the authority and duty to enforce Maryland’s Insurance Article. The Insurance Commissioner’s authority extends to conducting examinations and investigations as necessary to fulfil this purpose.
In addition to direct regulation by the Insurance Commissioner, the Maryland General Assembly created a People’s Insurance Counsel Division (PICD) in the Office of the Attorney General. The PICD exists to protect people insured under policies of medical professional liability insurance and homeowner’s insurance issued or delivered in Maryland and is authorised to appear before the Insurance Commissioner on behalf of insurance consumers. The PICD is responsible for reviewing and evaluating each medical professional liability insurance and homeowner’s insurance matter pending before the Insurance Commissioner to determine whether insurance consumers’ interests are affected and is required to review any rate increase of 10% or more by any medical professional liability insurer or homeowner’s insurer.
Although the statutory language regarding the PICD’s authority is not entirely clear, the Supreme Court of Maryland has determined the PICD has standing to request a hearing before, and file a petition for judicial review from an adverse decision of, the Insurance Commissioner. The PICD’s opposition to a professional liability or homeowner’s filing can present additional challenges for insurers, but the Supreme Court of Maryland has demonstrated a willingness to correctly apply the law and disregard misguided arguments from the PICD.
The PICD’s authority to appear before the Insurance Commissioner is significant because the Maryland Insurance Administration (MIA), under the direction of the Insurance Commissioner, has an established process for administrative complaints alleging violations of the Maryland Insurance Article. The MIA investigates such complaints and initially determines whether a violation of Maryland insurance law occurred.
Anyone “aggrieved” by an investigative determination may request a hearing, which is a quasi-judicial proceeding with limited discovery. A hearing request must set forth “[t]he action or non-action of the Commissioner causing the person requesting the hearing to be aggrieved”, and “[t]he ultimate relief requested”. A defective hearing request could be denied, but the MIA rarely enforces this type of procedural deficiency, and it is often overlooked in consumers’ requests for hearings.
The Insurance Article grants the Insurance Commissioner broad remedial powers for violations of the Insurance Article, including imposing fines for each violation that is arbitrary and capricious and for violations committed with such frequency as to indicate a general business practice. A party dissatisfied with a final order of the Insurance Commissioner can seek judicial review in a Maryland circuit court.
In 2026, the Maryland General Assembly enacted legislation granting authority to the “Administration”, as opposed to the Insurance Commissioner, to issue certain orders. After the Administration issued an order, that order was challenged, among other grounds, as an unlawful delegation to the Administration in violation of the Maryland Constitution’s separation of powers doctrine. Although the General Assembly failed to provide an administrative remedy for “Administration” orders, the Administration has recognised its orders are subject to the same hearing rights and requirements as orders issued by the Insurance Commissioner. Challenges to this legislation are ongoing and worth watching.
A private party cannot circumvent the comprehensive remedial scheme established under the Insurance Article by pursuing a private cause of action. If a statute provides a special form of remedy, then a plaintiff must use that form; when a statutory remedy is provided, that remedy is exclusive. An individual cannot pursue a tort action for damages in court based on the same issues advanced or that should have been advanced in an administrative proceeding. According to the Supreme Court of Maryland, state insurance laws regulating claims practices are “in the nature of governmental regulations and [do] not create private rights of action”. The Supreme Court of Maryland, however, has recognised that common law claims for fraud, negligent misrepresentation, and negligence arising out of the sale of insurance are independent of the Insurance Article and are not subject to the doctrine of pursuit and exhaustion of administrative remedies.
At the same time, the Appellate Court of Maryland, in Matter of Holder, 268 Md. App. 595 (2026), recently recognised a party is collaterally estopped from challenging the factual findings in a final decision by the Insurance Commissioner. The case arose from a proceeding initially premised on unfair insurance claim practices, but the insurer was found not to have violated Maryland law because the underlying lawsuit giving rise to the alleged unfair practice involved allegations of intentional acts by the insured, which were not covered by the policy and could not possibly give rise to a duty to defend. Rather than seek judicial review of that decision, the insured filed a new proceeding with the Insurance Commissioner alleging the denial of coverage was not in good faith based on a different Insurance Article provision.
In the second case, an Administrative Law Judge ruled the insurer could not have violated this other provision of the Insurance Article because the prior proceeding already determined there was no insurance coverage and no duty to defend. Since no coverage existed in the first place, the denial of coverage could not have been without good faith. The insured filed a petition for judicial review from this second decision. After filing the petition for judicial review, the insured filed an amended complaint adding new civil law claims. The Circuit Court affirmed the Administrative Law Judge’s decision and dismissed the amended complaint. On appeal, the Appellate Court of Maryland confirmed the second proceeding was barred by collateral estoppel and that the insured could not raise new civil claims in an amended complaint in a petition for judicial review.
Although the complex administrative litigation environment in Maryland can sometimes be costly and challenging, Maryland compensates for this inconvenience to some degree by not recognising a cause of action against an insurer for bad faith failure to pay a first-party insurance claim. Maryland has made a considered decision not to recognise a tort action for bad faith failure to settle with an insured in the first-party context. Even a bad faith negligence claim against an insurer by a third-party beneficiary is considered a “first-party” claim because the beneficiary “stands in the shoes of the insured”. This is important because Maryland does not recognise a tort action against an insurer for bad faith failure to pay an insurance claim.
The Supreme Court of Maryland has further recognised that the duty owed by an insurer who “mistakenly denies coverage... to the insured” is “entirely contractual”. An insurer’s mistaken failure to provide a defence based on the belief that there is no insurance contract or no insurance coverage exists does not give rise to a tort claim for bad faith. Any such claim for coverage sounds in contract and is limited to the coverage policy limits and defence costs.
Maryland law further holds that the insured-insurer relationship is not fiduciary in nature. Absent any special (fiduciary) relationship between the parties, Maryland courts have not ordinarily been willing to impose an affirmative duty to protect the interests of another.
Property and casualty insurance policies and individual disability insurance policies issued, sold or delivered in Maryland can be the subject of a statutory claim for lack of good faith. By statute, good faith is defined to mean: “an informed judgment based on honesty and diligence supported by evidence the insurer knew or should have known at the time the insurer made a decision on a claim”. This statute only applies to first-party claims between an insured and a property, casualty, or disability insurer, not to third-party claims. As a matter of law, however, an insurer cannot have failed to act in good faith based on any delay in determining coverage or payment if the insurer acted within the time specified by statute or regulation. Compliance with the statutory or regulatory timeline is a complete defence to a lack of good faith claim based on a delayed decision.
In a lack of good faith action, an insured can recover “actual damages”, up to the policy limits, along with attorneys’ fees, expenses, litigation costs, and interest. This claim is again subject to an administrative exhaustion requirement. For this reason, a circuit court action can only be commenced after a final decision by the MIA. Any circuit court appeal of an MIA decision is de novo. A party may also elect to have the case tried by a jury in the Circuit Court.
Maryland recognises a tort claim for bad faith in connection with third-party liability insurance. An automobile liability insurer, for example, may be subject to a claim of bad faith if it fails to resolve a claim within policy limits. Maryland, however, has not allowed premature filing of bad faith claims where there has been no excess judgment and the insurer is continuing to provide a defence. Maryland also recognises that an insurer’s offer to settle for the policy limits before entry of an excess verdict will generally insulate an insurer from a bad faith claim.
Maryland’s unique legal landscape also limits property and casualty insurers from restricting underperforming producers by both restricting cancellations or amendments of producer agreements based on adverse loss ratios and prohibiting cancellations or amendments of producer agreements, or refusal of business from an insurance producer, for arbitrary, capricious, unfair, or discriminatory reasons.
The MIA has sanctioned insurers for restricting agents’ ability to place business with an insurer where the restriction results in agents not placing business with the insurer that qualified under the insurer’s underwriting guidelines and for which the insurer has a filed and approved rate, regardless of whether the insurer characterised the restrictions as unrelated to underwriting. Insurers cannot encourage appointed agents to adopt agency underwriting guidelines inconsistent with the insurer’s general underwriting guidelines and filed rates, or apply agency-specific underwriting requirements/scores, loss ratio benchmark requirements, or impose disciplinary programmes that might result in an agency not placing business with the insurer which qualifies under its underwriting guidelines and filed and approved rating plan.
Insurers seeking to take agency-specific actions, whether formal or informal, must be careful not to run afoul of Maryland’s prohibition on the application of loss-ratio standards and avoid taking action that requires or encourages agencies not to place business with the insurer that qualifies under the insurer’s underwriting guidelines and filed rating plan. If an agency files a complaint with the MIA, then the same administrative litigation process applies to the agency complaint.
Maryland laws aimed at preventing unfair underwriting discrimination prohibit insurers from cancelling or refusing to underwrite or renew particular insurance risks or classes of risk except by the application of standards reasonably related to the insurers’ economic and business purposes. The MIA has interpreted the “economic and business purposes” standard to prohibit an insurer from refusing to underwrite a risk if the insurer has a filed and approved rate applicable to that risk. If an insurer’s rating rules provide a rate for the risk, then the insurer cannot reject that risk, either directly or through agent underwriting, and regardless of whether it is a declination or non-renewal.
Both Maryland courts and insurance regulators have become actively involved in addressing the legal landscape surrounding artificial intelligence (AI) in litigation and in the insurance industry. The US District Court for the District of Maryland (the “Court”) recently issued Standing Order 2026-03 (the “Order”) addressing the use of AI in court filings. The Order states that when litigants present a pleading, written motion, or other paper to the court, they are certifying the legal positions are warranted by existing law and factual representations have evidentiary support pursuant to Federal Rule of Civil Procedure 11. Despite this “clear directive”, the Order notes how litigants, increasingly relying on generative AI, have submitted filings that “include non-existent case citations, fake quotations, and unsupported factual assertions”. The Order cautions attorneys and unrepresented parties to verify the accuracy of all filings prior to submission, “especially when relying on AI”, and notes that filings with “fake or hallucinated citations, quotations, or representations may be subject to Rule 11 sanctions…”, including, inter alia, dismissal, filing restrictions, monetary sanctions, and any other sanction deemed appropriate by the presiding judge. Further, the presiding judge may refer attorneys to the Court’s Disciplinary and Admissions Committee for investigation and appropriate discipline for related violations.
In 2024, the MIA also adopted guidance on the use of AI by insurers. Maryland Insurance Bulletin No. 24-11 reminds carriers they must comply with all applicable insurance law and regulations, including unfair trade practices and unfair discrimination laws, when making decisions or taking actions impacting consumers made or supported by advanced analytical and computational technologies. The Bulletin sets forth the MIA’s expectations as to how carriers will govern the development/acquisition and use of certain AI technologies and advises carriers of the type of information and documentation the MIA may request during an investigation or examination of any carrier regarding its use of such technologies and AI systems. The MIA is also participating in a pilot programme from March to September 2026 to test and gather feedback on a new AI Systems Evaluation Tool (the “AI Tool”) developed by the National Association of Insurance Commissioners (NAIC). The AI Tool is intended to provide a structured way for regulators to understand how insurers use AI, assess the effectiveness of governance practices in managing related risks, and identify where additional oversight, training, and improvements may be needed. The AI Tool is slated to be considered for adoption at the NAIC’s National Meeting in November 2026.
From a traditional judicial litigation perspective, the Supreme Court of Maryland has long followed the law of objective interpretation of contracts. The Supreme Court of Maryland’s recent insurance decisions continue to reflect the court’s contract-focused perspective. The Supreme Court of Maryland’s decision in CareFirst BlueChoice, Inc. v Skipper, 493 Md. 681 (2026), however, recognises that insurance contract language designed to meet statutory or regulatory requirements cannot be read in isolation, but must be read in the context of the related statutory and regulatory language.
In Bowens v State Farm Mutual Automobile Insurance Company, 492 Md. 608 (2025), the Supreme Court of Maryland considered whether, for purposes of determining the Maryland District Court’s USD30,000 jurisdictional threshold under § 4-401(1) of the Maryland Courts and Judicial Proceedings Article (CJP), the phrase “debt or damages claimed” included only the amounts a plaintiff sought to recover in uninsured or underinsured (UIM) benefits from his own insurer, or also included sums previously paid to the insured by a tortfeasor’s liability insurer. George Bowens was injured in an automobile accident with an underinsured motorist, who the parties agreed was negligent. The underinsured motorist had automobile liability insurance with a USD30,000 limit; this sum was offered to Bowens in satisfaction of his claims against the underinsured motorist. Bowens forwarded the settlement offer to his UIM carrier, State Farm Mutual Insurance Company (“State Farm”), which consented to settlement and waived subrogation pursuant to procedures established for UIM coverage under Maryland’s Insurance Article. Bowens accepted the USD30,000 policy limits settlement offer, then filed a claim with State Farm for the remaining USD20,000 available under his own USD50,000 UIM policy.
State Farm denied his claim. Bowens then filed a breach of contract lawsuit against State Farm in the District Court of Maryland, which has jurisdiction over contract claims “if the debt or damages claimed do not exceed USD30,000”. CJP § 4-401(1). State Farm moved to dismiss, arguing Bowens needed to prove total damages of USD50,000 from the auto accident in order to recover the remaining USD20,000 available under his UIM coverage. The District Court granted the motion to dismiss, finding a lack of subject matter jurisdiction. The Circuit Court affirmed.
The Supreme Court of Maryland disagreed. The Court examined the meaning of “debt or damages claimed” under CJP § 4-401(1) in conjunction with the UIM provisions of the Insurance Article, which permit an insured to accept a tortfeasor’s settlement without prejudicing a residual claim against the UIM carrier. The Court characterised Bowens’ case as “a first-party coverage dispute—a breach-of-contract action against his insurer—not a tort action”. Bowens, 492 Md. 608, 624. The Court noted that Bowens’ acceptance of the tortfeasor’s USD30,000 settlement – and State Farm’s consent thereto pursuant to the Insurance Article provisions – extinguished any claim against the tortfeasor for that portion of his injuries and capped State Farm’s UIM contractual liability at USD20,000. Ultimately, the Court held the phrase “debt or damages claimed” in CJP § 4-401(1) is measured by the amount the plaintiff seeks from the defendant in the pending action. Since Bowens’ residual UIM claim fell within the District Court’s USD30,000 jurisdictional limit, the Court reversed the Circuit Court’s judgment and remanded the case for further proceedings.
In CareFirst BlueChoice, Inc. v Skipper, 493 Md. 681 (2026), the Maryland Supreme Court reviewed a denial of coverage by CareFirst BlueChoice, Inc. (“CareFirst”) for embryo thawing as part of an in vitro fertilisation (IVF) cycle. The Skippers sought coverage for embryo thawing under their CareFirst health insurance policy, which CareFirst denied based on a policy exclusion for “[o]vum transplants and gamete intra-fallopian tube transfer, zygote intra-fallopian transfer, or cryogenic or other preservation techniques used in these or similar procedures”. The Skippers received the IVF treatment and paid out-of-pocket for the cost of the embryo thawing procedure.
Two years later, the Skippers appealed CareFirst’s denial of the embryo thawing procedure, which CareFirst denied as untimely as it was filed beyond the 180-day period allowed by the policy. Id. The Skippers then filed a complaint with the MIA and, while that MIA complaint was pending, filed a class action lawsuit in the United States District Court for the District of Maryland.
Shortly after the federal court complaint was filed, CareFirst issued a new claim determination and reimbursed the Skippers’ medical provider for the cost of the embryo thawing. Id. at 691. Based on that change in position, the MIA closed the Skippers’ complaint. The District Court also dismissed the federal class-action complaint, ruling it lacked jurisdiction because the claims failed to meet the applicable damages threshold for federal class-action lawsuits.
The Skippers then filed a state court complaint in Maryland Circuit Court, which mirrored the claims and proposed class definition of their federal suit. CareFirst moved to dismiss the state court complaint for mootness based on the reimbursement for the embryo thawing claim. The Circuit Court granted CareFirst’s motion to dismiss, finding the reimbursement mooted the claim. The Appellate Court of Maryland reversed, holding the claim was not moot because the USD900 payment did not satisfy the Skippers’ claims for pre-judgment interest, declaratory relief, and injunctive relief.
The Supreme Court of Maryland affirmed, finding the Skippers had standing to pursue their claims. The Supreme Court ruled the policy exclusion was not a valid ground for CareFirst’s denial of the embryo thawing procedure because Md. Code Ann., Ins. § 15-810(c) prohibited CareFirst from excluding all outpatient expenses arising from IVF procedures and required CareFirst to cover IVF expenses “to the same extent as the benefits provided for other pregnancy-related procedures”.
In its opinion, the Supreme Court also noted that, under existing Maryland precedent, Frazier v Castle Ford, 430 Md. 144 (2013), “a class action defendant’s tender of individual relief to a putative class representative does not moot a class action lawsuit before the representative has a reasonable opportunity to seek class certification”. The Supreme Court extended this holding to circumstances in which “a putative class action is initially filed in another court, dismissed in that court for lack of jurisdiction, and promptly refiled in substantially the same form in state court”.
Maryland insurance litigation presents complex choice-of-forum questions that are different from most other jurisdictions. Beyond forum choice, many of the regulatory and statutory requirements and deadlines are jurisdictional, and the failure to strictly adhere to them can result in dismissal of the proceedings. Engaging experienced insurance counsel is critical to identifying and avoiding the pitfalls that are part of Maryland’s insurance law landscape.
Funk & Bolton, P.A.
Suite 1400
100 Light Street
Baltimore
Maryland 21202
USA
410-659-7700
410-659-7773
rtundermann@fblaw.com www.fblaw.com
Trends and Developments
Authors
Funk & Bolton, P.A. offers client services across the spectrum of insurance regulation, insurance litigation, legislative services, and creditors’ rights. The insurance group offers a unique perspective on Maryland insurance law, pairing legislative, regulatory, and litigation expertise inside a boutique law firm with offices in Baltimore and Annapolis. Maryland insurers engage the firm to perform regulatory, compliance, and litigation work in Maryland and beyond, while national insurers engage the firm for its Maryland insurance expertise. The firm provides guidance to insurance entities from concept through formation, incorporation, and licensure, including form and rate filings. The firm supports insurers in market conduct and financial examinations, regulatory proceedings, consumer complaints, holding company act issues, boards and committees. The firm represents insurers in litigation in administrative proceedings, and state and federal court. The firm regularly handles M&A transactions and complex restructurings, including reinsurance transactions. The firm is regularly engaged to serve as litigation counsel for national and international insurers on important questions of Maryland law.