Insurance Litigation 2026
USA – New Jersey
Trends and Developments
Author
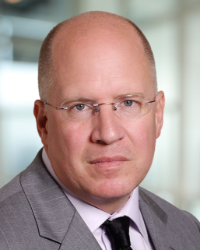
Pollock Law, LLC is a sole proprietor litigation firm with offices in Trenton, New Jersey and Babylon, New York, established in 2024 by Jeffrey M. Pollock after three decades of complex litigation practice at larger New Jersey firms. In addition to Mr Pollock, the firm has two full-time paralegals and the office dog, Lilah. The firm represents policyholders in first-party and third-party coverage disputes, including commercial general liability, directors and officers, errors and omissions, business interruption and environmental coverage, and it also litigates the underlying liabilities those policies respond to. Its environmental practice covers CERCLA, RCRA and ISRA matters, including Superfund allocation and natural resource damages, which generate the long-tail coverage claims the firm handles. Related work includes appellate advocacy, arbitration and mediation, shareholder and fiduciary disputes, and First Amendment litigation. Over his career, the firm’s founder has recovered more than USD650 million for policyholders in declaratory judgment actions and defended Superfund and Spill Act matters carrying over USD220 million in exposure.
New Jersey: A Policyholder Reputation That Has Outlived Its Evidence
The claim worth testing
New Jersey’s courts carry a reputation, built over four decades, as among the most hospitable in the United States to policyholders. That reputation rests on real landmarks: (i) the continuous-trigger doctrine for progressive injury; (ii) the rule that courts read exclusions narrowly against the insurer that drafted them; and (iii) a reasonable expectations doctrine that overrides literal language. Businesses insuring New Jersey risks still price that reputation into where they sue and what they accept to settle.
The decisions of the last four years are significantly less policyholder-friendly. Although New Jersey has not become an insurer’s jurisdiction, the recent court rulings are worth noting for both carriers and policyholders. This article addresses how counsel should plan, plead and resolve coverage disputes. It argues further that the federal courts sitting in New Jersey, which practitioners have long assumed to be the tougher forum, treat policyholders more sceptically than the state courts do, and always have.
The pandemic cases set the pattern
The COVID-19 pandemic produced the largest simultaneous test of first-party coverage in New Jersey’s history, and policyholders lost it comprehensively. The Appellate Division moves first in Mac Property Group v Selective Fire and Casualty Insurance Co (App Div, 20 June 2022), holding that closure orders cause no direct physical loss of or damage to restaurants, a bakery, a gym and a childcare centre. The court rejects civil authority coverage, declines to apply regulatory estoppel to virus exclusions, and enforces the exclusions as written. One opinion addresses and rejects every doctrinal lever a policyholder might pull.
The Supreme Court closes the question in AC Ocean Walk v American Guarantee and Liability Insurance Co (24 January 2024). A casino operator seeking roughly USD50 million loses unanimously, and loses at the pleadings stage. The Court holds both that the closure caused no direct physical loss or damage and, independently, that the contamination exclusion applies on the face of the complaint. That second holding matters more than the first, because it converts a fact-intensive coverage dispute into a Rule 4:6-2(e) question.
The Third Circuit reached the same destination a year earlier by a different route. In Wilson v USI Insurance Service LLC (6 January 2023), it consolidates appeals from businesses across New Jersey and Pennsylvania and predicts that neither state’s highest court will treat loss of intended use as physical loss. The federal prediction thus precedes the state court’s answer by more than a year, a pattern this article takes up below.
The posture deserves more attention than the outcome. A jurisdiction genuinely committed to construing coverage grants broadly and exclusions narrowly does not ordinarily resolve a novel first-impression exclusion dispute on the pleadings. Policyholder counsel should read AC Ocean Walk as a signal about procedure as much as substance:
- Exclusions now defeat a complaint before discovery, where they once served as affirmative defences requiring a record.
- Pleading the insurer’s own drafting history, underwriting materials or regulatory representations no longer reliably survives a motion to dismiss.
- The reasonable expectations doctrine did not rescue a sophisticated commercial policyholder that sophisticated brokers advised.
Exclusions are now read broadly
The narrow-construction canon is where the erosion shows clearest. In Norman International v Admiral Insurance Co (10 August 2022), the Supreme Court enforces a designated-counties exclusion barring claims “in any way connected with” the insured’s operations in excluded territory. The Court holds that the phrase requires no causal relationship, because a tangential link suffices. It holds further that an insurer may rely on undisputed extrinsic facts to defeat the duty to defend rather than confining itself to the four corners of the complaint.
That relocates the burden significantly. The mere potential for coverage on the face of the pleadings had long triggered New Jersey’s duty to defend, and courts resolved doubts in the insured’s favour. Norman International lets an insurer look outside those pleadings to establish that no potential exists, so an insurer can now deny a defence at the outset on facts the insured has had no chance to contest through discovery.
MIST Pharmaceuticals v Berkley Insurance Co (11 May 2026) extends the same logic to directors and officers cover over a substantial dissent. Berkley funded a defence for roughly five years before disclaiming under a capacity exclusion barring claims “in any way involving” wrongful acts the insured person committed in his capacity at entities other than the named insured. The Court holds the exclusion unambiguous, requires no causal nexus between the excluded capacity and the alleged harm, and finds no estoppel because Berkley reserved its rights repeatedly and explicitly throughout. Justice Fasciale, joined by Justice Hoffman, dissents at length: exclusions demand narrow construction, ambiguity should favour coverage, and estoppel should bar an insurer that signalled partial coverage for years from asserting a total bar.
The dissent is the most useful document in the case for policyholder counsel because it identifies what the majority sets aside. Read together, Norman International and MIST establish that expansive connective phrasing – “in any way connected with”, “in any way involving”, “arising out of”, “related to” – now carries its literal breadth in New Jersey. Insurers drafting exclusions have their instruction, and they will follow it. The counter-argument – that both cases merely enforce unambiguous language and that ambiguity would still favour the insured – holds as far as it goes; it simply concedes that the threshold for finding ambiguity has risen materially.
Merck is the exception that proves the point
Merck & Co v ACE American Insurance Co (App Div, 1 May 2023) remains the most celebrated recent policyholder victory in the state. The Appellate Division holds that a hostile or warlike action exclusion does not bar coverage for losses exceeding USD1.4 billion that the NotPetya malware caused, even accepting that the attack traces to the Russian Federation. No court had applied such exclusions outside clear war or concerted military action, and the insurers, having never updated decades-old language against well-known state-sponsored cyber risk, could not stretch it to reach a commercial pharmaceutical business.
But Merck is a weaker precedent than its reputation suggests, for two reasons policyholder counsel should state candidly to clients:
- It is an Appellate Division decision. The Supreme Court granted certification and the parties settled in January 2024, so the state’s highest court never ruled.
- Events have overtaken its central rationale that insurers failed to update their language, because the London and US markets now deploy express cyber and state-backed attack exclusions.
Merck rewarded insurer neglect at a moment when that neglect was general. It will not do the same work against the exclusions now in the market, and New Jersey will receive those exclusions, on the evidence of Norman International and MIST, considerably more warmly than Merck implies.
The settlement itself teaches how coverage law now gets made. An insurer facing an adverse intermediate decision has every incentive to settle before an affirmance, and a policyholder holding a large intermediate win has every incentive to take the money. The questions most worth answering therefore reach a court with authority to answer them least often.
The Fair Conduct Act: a legislative correction, judicially paced
The legislature, not the judiciary, produced the period’s genuine expansion of policyholder rights. The Insurance Fair Conduct Act, signed on 18 January 2022, gives uninsured and underinsured motorist claimants a private right of action against insurers for unreasonable delay or unreasonable denial. It authorises damages up to three times the coverage amount, plus interest, attorneys’ fees and litigation expenses. That intervention is itself evidence for the thesis, because the legislature acted only after concluding that the common-law bad faith standard fell short.
The Appellate Division gives the statute a genuinely favourable construction in Tenenbaum v Allstate Insurance Co (29 April 2026). The court rejects the insurers’ argument that the Act merely restates the common-law standard, holding instead that it creates a distinct statutory cause of action, incorporates violations of the Unfair Claims Settlement Practices Act, and does not import the “fairly debatable” test the Legislature plainly knew about when it legislated. On the elements, that is a real policyholder win.
The procedural half of Tenenbaum recovers the advantage. The court holds that statutory claims remain subject to the established practice of severance and stay pending resolution of the underlying UM or UIM claim, because deferring costly discovery promotes judicial economy. A treble-damages remedy counsel cannot investigate until the underlying claim concludes carries materially less weight in settlement than the statute’s text implies. Earlier, the federal court holds in Roach v Allstate Insurance Co (D.N.J., 8 December 2023) that the Act does not reach conduct predating its effective date.
Two unsettled questions now drive Fair Conduct Act practice. The first asks whether courts can extend the Act beyond UM and UIM claims into other first-party lines; the statutory text confines it, and any expansion belongs to the legislature. The second asks whether the Supreme Court will endorse Tenenbaum’s separation of the statutory standard from the common law or reabsorb the Act into the Pickett v Lloyd’s framework. Counsel should treat the favourable half of Tenenbaum as provisional until that happens.
The common-law standard the Act supplements remains demanding. Under Pickett v Lloyd’s, an insured must show that the insurer had no fairly debatable reason to deny or delay, and a genuine coverage dispute defeats the claim. Insurer-side commentary describing New Jersey’s bad faith threshold as a high bar states the current authorities accurately rather than aspirationally. Read the Fair Conduct Act in that context: a targeted fix for one line of business that leaves the general standard untouched.
The regulatory layer
Legislative and regulatory activity moves faster than the case law, and clients feel it sooner. New Jersey raises compulsory automobile limits in stages under P.L. 2022, c. 87, to USD25,000/50,000/25,000 for policies issued or renewed from 1 January 2023, and to USD35,000/70,000/25,000 from 1 January 2026. The Department of Banking and Insurance separately raises minimum limits for heavy commercial motor vehicles and autocabs to a USD1.5 million combined single limit, effective 1 July 2024.
Higher compulsory primary limits compress the layer in which UIM disputes arise, which should shrink the pool of claims the Fair Conduct Act polices. Higher commercial motor limits raise the stakes in trucking and livery disputes.
Underwriting inputs remain the most politically exposed question in the state. Senate Bill 2248 would bar insurers from setting automobile rates by reference to credit history, education, occupation, marital status and postcode. It has passed the Senate in earlier sessions, has never moved in the Assembly, and drew a further committee hearing in June 2026. Treat it as a live risk to insurer pricing models rather than an imminent change in the law.
Disclosure obligations have already moved. Under P.L. 2021, c. 98, authorised insurers must give commercial policyholders a Department-issued summary of common business interruption clauses, triggers and exclusions. That summary expressly does not alter the coverage the policy affords, which limits its use in an estoppel or reasonable expectations argument. Its likelier value is evidential, as a benchmark against which to measure an insurer’s own pre-sale communications.
Solvency regulation drives the sharpest current fight. In December 2025, the Department adopted amendments extending the Insurance Holding Company Act to reciprocal exchanges and requiring reciprocals to set attorney-in-fact fees on an arm’s length, fair and reasonable basis under SSAP No 25. Citizens United Reciprocal Exchange challenged the rules and won a stay from the Appellate Division in March 2026, which the Supreme Court vacated on 10 April 2026. The rules govern while the challenge proceeds, and the result will determine how far New Jersey can regulate the fee structures of reciprocals writing personal lines here.
Arbitration and the boundary of what counts as insurance stay active. Federal courts in New Jersey continue to enforce arbitration provisions in commercial policies under federal law, and hold that joint insurance funds providing self-insurance are not “insurance” for coverage analysis, most recently in National Union Fire Insurance Co of Pittsburgh, PA v Somerset County Joint Insurance Fund (D.N.J., 21 August 2026). Public entities and pooled risk-sharing arrangements should not assume that coverage doctrines built for commercial policies transfer.
Climate, coast and the economics of rebuilding
New Jersey’s sea levels rise at roughly twice the global average, and exposure concentrates where the economy does: the ports, the shore counties and the industrial waterfront. That physical fact now drives regulation. In January 2026, the Department of Environmental Protection adopted the NJPACT REAL rules, which require new coastal development to sit roughly four feet above FEMA’s 100-year base flood elevation and impose assessment obligations in projected inundation zones. They follow the Inland Flood Protection Rule of 2023 and carry a contested hardship exception for affordable housing.
These rules will change coverage litigation more than environmental practice. Higher rebuilding standards enlarge ordinance or law claims, because restoring a damaged structure to current code now costs materially more than restoring it as it stood. They also sharpen the boundary G.E.M.S. Partners narrowed, since the line between excluded flood and covered water damage decides who absorbs that difference. Read ordinance or law sublimits, and the definitions of flood and surface water, as the provisions likeliest to carry the cost of New Jersey’s adaptation policy.
Federal courts were never the friendlier forum
The premise that federal courts in New Jersey favour policyholders less is not new, and the pandemic litigation exposes the mechanism precisely. When district courts in this Circuit tried to return novel state-law coverage questions to the state courts that owned them, the Third Circuit stopped them. In DiAnoia’s Eatery v Motorists Mutual Insurance Co (18 August 2021), the court holds that the district courts abused their discretion under the Declaratory Judgment Act, vacates the remand orders, and directs renewed consideration of the Reifer factors.
Burlington Stores v Zurich American Insurance Co (D.N.J. 2022) illustrates the downstream effect, where the court retains jurisdiction over a New Jersey COVID-19 coverage dispute. Reasoning that the governing principles of New Jersey insurance law summarise easily and travel across states, and that federal decisions had by then supplied ample guidance, the court declines to abstain.
That states the structural problem in a sentence. Federal courts generated most of that guidance by predicting state law, and it hardened into consensus before the New Jersey Supreme Court spoke. The reasoning turns circular in a way that is easy to miss: novelty defeats abstention only until enough federal courts answer the novel question, at which point the answer is no longer novel. The Reifer factors and the guidance of State Auto Insurance Cos v Summy direct federal courts to hesitate where state law remains undetermined, and New Jersey practice runs the other way.
Erie prediction is not a neutral technology, and the cases show its bias:
- In G.E.M.S. Partners v AmGUARD Insurance Co (D.N.J. 2024), the court predicts that the New Jersey Supreme Court would define “flood” and “surface water” in a way that narrows the coverage grant, on a question the state’s highest court has never decided.
- In Ascot Specialty Insurance Co v Mason, Griffin & Pierson (D.N.J., 18 August 2025), the court applies a purely objective standard to a professional liability prior knowledge exclusion, displacing New Jersey’s hybrid subjective-objective formulation in favour of the policy’s own language.
- In Kimmel v Massachusetts Bay Insurance Co (D.N.J. 2025), the court holds that replacement cost estimates standing alone do not establish actual cash value, raising the evidentiary burden on a first-party insured at summary judgment.
Federal courts also reach results that favour policyholders, and intellectual honesty requires saying so. South Millville Properties v Westchester Surplus Lines Insurance Co (D.N.J. 2023) applies New Jersey’s efficient proximate cause rule to hold that a copper theft exclusion does not bar fire loss, and Navigators Specialty v Citizens Insurance Co of America (D.N.J. 2024) reads additional insured coverage to reach direct as well as vicarious liability. The point is not that federal courts always rule for insurers, but that a federal court deciding an unsettled question of New Jersey law makes a prediction, predictions in this Circuit tend toward the restrictive, and the policyholder bears the consequence without a state forum to correct it.
Certification corrects this, and it works when counsel use it. In Chiaccheri v Zurich American Insurance Co (6 August 2026), the Supreme Court answers certified questions from the Third Circuit on commercial auto UIM limits, holding that the statutory parity requirement runs between the named insured’s UIM limit and the employee’s, not between UIM coverage and third-party liability limits. The policyholder lost, which is precisely why the case instructs: certification guarantees an authoritative answer, not a favourable one. Counsel facing an unsettled question in federal court should press for certification early, before a federal consensus forms that makes the question look settled.
What still cuts for policyholders
The thesis would be dishonest without the counterweight, and the counterweight is real. Courts still apply the ambiguity rule with force. In Motil v Wausau Underwriters Insurance Co (App Div, 2024), the court refuses to enforce a UIM step-down provision because the declarations page creates a reasonable expectation of full limits that conflicting language elsewhere cannot defeat. The reasonable expectations doctrine is not dead; it simply does less work in commercial disputes than in personal lines.
Long-tail coverage remains the strongest ground. In Northfield Mass Associates v Travelers Indemnity Co (Law Div, 30 October 2025), the court holds non-cumulation clauses unenforceable in construction defect cases involving progressive and indivisible damage, extending Spaulding Composites v Aetna beyond environmental contamination. The court weighs the effect of the clauses rather than their labels, refusing to let drafting cosmetics defeat the continuous-trigger doctrine. It is a trial-level ruling and carries the precedential weight that status implies, but its reasoning is orthodox New Jersey law and counsel should cite it.
The strongest response to everything argued here deserves its best statement. New Jersey’s canons were never rules of outcome, only rules of construction; AC Ocean Walk, Norman International and MIST each involve language the courts find unambiguous, and New Jersey has always enforced unambiguous language; a run of insurer wins over four years is a sample, not a shift; and the Fair Conduct Act shows the system correcting itself. That argument carries real force, and no honest advocate should pretend otherwise.
It is answerable. The question is never whether a court enforces unambiguous language, but how readily it finds language unambiguous, and on that measure the movement runs one way. A court that finds “in any way connected with” clear enough to require no causal nexus, that lets extrinsic evidence defeat a defence, and that disposes of a first-impression exclusion on the pleadings has moved the threshold, whatever it says about the canons. Refuting the thesis takes a decision in which the Supreme Court declines to enforce a deliberately broad exclusion in a commercial dispute, and this period has produced none.
A bifurcated jurisdiction emerges. New Jersey’s traditional protections hold where the doctrine is settled, the policyholder is unsophisticated, or the coverage question involves progressive injury across policy periods. They weaken where the dispute is commercial, the insurer drafted the exclusion broadly and deliberately, and the question is new.
Practical consequences
Five consequences follow for anyone litigating New Jersey coverage.
- Treat forum as a merits decision. Where a policyholder can defeat diversity, keep the case in the Law Division. Where removal looms, plan for certification from the outset rather than after an adverse prediction.
- Assume courts read exclusions literally. Connective phrases carry full breadth. Ambiguity arguments must identify genuinely competing readings, not merely unattractive results.
- Plead the record into the complaint. After AC Ocean Walk, matters counsel once reserved for discovery must appear at the pleadings stage or may never surface.
- Attack the reservation of rights early. The quality of the insurer’s correspondence decided MIST. Where reservations run generic, stale or silent as to the exclusion the insurer later invokes, estoppel and forfeiture stay live.
- Do not treat Merck as a shield against modern cyber exclusions. It addressed obsolete language. Current wordings demand a different attack, most plausibly on attribution standards and the burden of proving state sponsorship.
Conclusion
New Jersey has not turned against policyholders. It has stopped being unusual. Its canons remain on the books, but the Supreme Court has spent four years reading broad exclusionary language according to its terms, letting extrinsic evidence defeat the duty to defend, and resolving novel coverage questions at the pleadings stage. The legislature, not the courts, delivered the period’s most significant expansion of policyholder rights, and the courts have paced its effect.
The federal courts have not changed at all; they have simply become more visible, because the volume of removed coverage litigation since 2020 exposed how much New Jersey insurance law now comes from judges predicting what New Jersey judges would do. Policyholders who plan around the reputation lose. Those who plan around the record – choosing the forum deliberately, pleading exhaustively, pressing certification, and attacking insurer conduct where the paper trail runs thin – do considerably better.
Pollock Law, LLC
400 Riverview Plaza
Suite 200
Trenton
New Jersey 08611
USA
+1 609 308 7300
Jeff@pollocklaw.net www.pollocklaw.net
Trends and Developments
Author
Pollock Law, LLC is a sole proprietor litigation firm with offices in Trenton, New Jersey and Babylon, New York, established in 2024 by Jeffrey M. Pollock after three decades of complex litigation practice at larger New Jersey firms. In addition to Mr Pollock, the firm has two full-time paralegals and the office dog, Lilah. The firm represents policyholders in first-party and third-party coverage disputes, including commercial general liability, directors and officers, errors and omissions, business interruption and environmental coverage, and it also litigates the underlying liabilities those policies respond to. Its environmental practice covers CERCLA, RCRA and ISRA matters, including Superfund allocation and natural resource damages, which generate the long-tail coverage claims the firm handles. Related work includes appellate advocacy, arbitration and mediation, shareholder and fiduciary disputes, and First Amendment litigation. Over his career, the firm’s founder has recovered more than USD650 million for policyholders in declaratory judgment actions and defended Superfund and Spill Act matters carrying over USD220 million in exposure.