Corporate & Commercial 2026
Finland
Authors
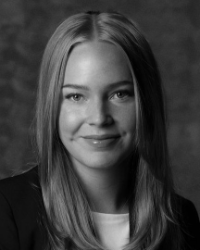
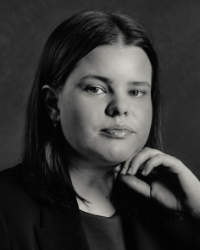
DKCO was founded in 1994 and is a boutique business law firm with its head office in Mariehamn on Åland and further offices in Helsinki and Vaasa. Corporate and commercial work is handled by eight to ten lawyers, including four partners, drawn from all three offices. The team advises on shareholder arrangements and corporate governance, commercial contracts, mergers and acquisitions, and transaction structuring and financing, drawing on the firm’s competition, procurement, permitting and disputes practices as mandates require. The lawyers work in Swedish, Finnish and English, which is particularly valuable for Swedish sponsors entering Finland and for Åland-connected structures. Recent work includes advising Stockholm Nordtech Midco AB on its acquisition of FinMeas Oy and acting for Silvestica Forest Finland Oy on land lease negotiations covering over 3,000 hectares of development-phase areas for industrial and renewable energy projects.
1. Business Entities
1.1 Business Organisations
The main Finnish business vehicles are the limited liability company (osakeyhtiö), the general partnership (avoin yhtiö), the limited partnership (kommandiittiyhtiö), the co-operative, the sole trader and the Finnish branch of a foreign company. The limited liability company is the standard form for commercial operations, as it is a separate legal person and its shareholders are not personally liable for its debts.
The choice of structure is driven by liability, tax treatment, governance flexibility, financing needs, any regulated activity and whether the business is owner-driven, member-driven (co-operative) or a foreign market entry (branch).
As regards liability, a limited liability company and a co-operative offer limited liability, whereas the partners in a general partnership are personally liable. In a limited partnership, at least one general partner is personally liable, while the liability of a silent partner is limited to its agreed contribution.
Limited liability companies and registered co-operatives are taxed as separate entities at the 20% corporate income tax rate (although the government submitted a proposal in September 2026 to reduce the rate to 18% from tax year 2027), whereas partnership income is generally allocated to the partners, and sole-trader income is taxed as the trader’s income.
1.2 Incorporation and Ongoing Compliance
To incorporate a private limited liability company (no minimum share capital required), founders must sign a written memorandum of association specifying the date, all shareholders and their subscribed shares, subscription price and payment deadline, board members and financial period. Articles of association must be attached. The company must be notified for registration with the Trade Register within three months, accompanied by a board declaration of compliance and an auditor’s certificate on share payment. The company is established upon registration. Concurrently, the company shall register with the Tax Administration for the prepayment register and, where the requirements for the respective register are met, the VAT register and the employer register.
Ongoing obligations include holding an annual general meeting within six months of the financial period’s end, among other things, to adopt financial statements. Financial statements must be filed with the Tax Administration and the Trade Register. The board must maintain a public shareholder register and promptly notify the Trade Register of changes to registered matters such as changes to the board composition.
1.3 Share Issuances
As limited liability companies are the primary corporate vehicle for Finnish commercial operations, the rules described in the following on companies governed by the Limited Liability Companies Act (624/2006) (the “Companies Act”). A public limited liability company must have share capital of at least EUR 80,000, while a private limited liability company has no statutory minimum. Shares may be issued by the general meeting or by the board under an authorisation granted by the general meeting specifying the maximum number of shares by class.
Finland does not use the Anglo-American concept of authorised share capital. Shares may be without nominal value; if the articles of association provide for a nominal value, it must be the same for all shares, and the share capital may not be lower than the aggregate nominal value. Subscription prices are credited to share capital unless, on incorporation, the memorandum of association or articles of association, or, in a subsequent share issue, the issue resolution, allocates them in whole or in part to the reserve for invested unrestricted equity.
Shares belong to different classes if they differ in voting rights or distribution rights, or if the articles of association so provide. The default rule is one share, one vote, but the articles may create high-vote, low-vote or non-voting classes, and may attach preferential dividend or liquidation rights and inter-class conversion rights to a class. Transfer restrictions in the articles are generally limited to consent and redemption clauses, so wider transfer controls are usually dealt with in shareholders’ agreements.
1.4 Distributions and Return of Capital
Under the Companies Act, distributions to shareholders are permitted only through statutory channels: dividends and distributions from the reserve for invested unrestricted equity, share capital reductions, acquisition/redemption of own shares and liquidation. Distributions must be based on the latest adopted and audited financial statements (taking into account material changes since completion) and may not exceed unrestricted equity less amounts required to remain undistributed under the articles or any capitalised development expenditure.
A mandatory solvency test applies: no distribution may be made if the company is or would become insolvent. Share capital reductions require a general meeting resolution and, unless used solely to cover losses, trigger a statutory creditor protection procedure.
Repurchase and redemption of own shares require general meeting approval, with board authorisations limited to 18 months and funded only from distributable assets (subject to the solvency test); treasury shares may be held, cancelled, or resold. A public company (including subsidiary holdings) may not hold more than one-tenth of all shares, with excess shares to be transferred within three years or cancelled; a private company may not acquire shares so that it holds all outstanding shares. Financial assistance for third-party acquisition of the company’s own shares or parent company shares is prohibited, except within distributable funds for employee share schemes.
1.5 Control Person Reporting
The main obligation for private companies in Finland to report control persons is to file details of actual beneficial owners with the Finnish Trade Register. A beneficial owner is a natural person who exercises control over a legal person by directly or indirectly owning more than 25% of the shares, or by directly or indirectly exercising more than 25% of the votes in the legal person or otherwise effectively exercising control of the legal person.
The company must file a notification even if it has no beneficial owners. The obligation to file details of beneficial owners does not apply to sole traders, companies traded on a regulated market or foreign traders that have established a branch in Finland.
2. Corporate Governance
2.1 Legal Framework
The Finnish corporate governance framework is addressed in the following primarily by reference to limited liability companies, and in particular public and listed limited liability companies, as these are the standard form for Finnish commercial operations. Other Finnish business vehicles, including partnerships, co-operatives, sole traders and Finnish branches of foreign companies, exist and are governed by their own entity-specific legislation.
The principal statute is the Companies Act, which governs private and public limited liability companies and sets out mandatory governance organs, shareholder decision-making, the equal-treatment principle and management duties and liability. The Accounting Act (1336/1997) governs financial statements and management reports, while the Auditing Act (1141/2015) regulates statutory audits. For listed companies, the Securities Markets Act (746/2012) (SMA), Market Abuse Regulation (EU) No 596/2014 (MAR) and Nasdaq Helsinki rules impose disclosure and market conduct obligations.
The key soft-law instrument is the Finnish Corporate Governance Code 2026, issued by the Securities Market Association. It applies to companies listed on Nasdaq Helsinki and to Finnish companies traded on Nasdaq First North Premier Growth Market on a comply-or-explain basis.
2.2 Directors’ Duties and Liabilities
Directors must act with due care and promote the interests of the company under the Companies Act. This statutory duty is commonly analysed as a duty of care and loyalty, reinforced by the equal-treatment principle, under which the general meeting, board, managing director or supervisory board may not confer an unjust benefit on a shareholder or another person at the expense of the company or another shareholder.
Finnish courts apply these duties fact-specifically, focusing on whether directors acted actively, informed themselves, supervised management and respected mandatory corporate procedures. In practice, the decisive question is typically whether the director acted in the best interests of the company on an informed basis.
A director, supervisory board member or managing director is liable to the company for damage caused intentionally or negligently in breach of the duty of care, and to the company, shareholders or third parties for damage caused intentionally or negligently by breaching the Companies Act or the articles of association. Personal liability may therefore arise from self-dealing, unlawful distributions, defective supervision, breach of equality or failure to react to serious financial distress.
2.3 Board Composition and Independence
A Finnish limited liability company must have a board of directors; unless the articles of association provide otherwise, the board has one to five ordinary members, and at least one member must reside in the European Economic Area (EEA) unless an exemption is granted. Legal persons, minors, persons under guardianship or restricted legal capacity and bankrupt persons are ineligible, and business prohibitions may affect eligibility.
Private companies are not subject to statutory independence or diversity requirements, although their articles of association or shareholder arrangements may impose governance requirements. Listed companies must additionally comply with the Finnish Corporate Governance Code on a comply-or-explain basis, which contains recommendations on board composition, including independence and diversity, that the board should take into account.
Public-interest entities, including listed companies within the Accounting Act definition, must also address audit committee requirements, including accounting or auditing expertise, independence and exclusion of persons participating in daily management.
2.4 ESG and Disclosure Obligations
The firm does not advise on ESG-matters.
2.5 Conflicts of Interest and Related-Party Transactions
Conflicts of interest are regulated by the general principles of the Companies Act, including the board’s duty of care, the equal-treatment principle and the Companies Act’s disqualification rules for board members and shareholders. For listed companies, the Companies Act contains more extensive and prescriptive related-party rules, under which conflicted related parties are excluded from decision-making on transactions that are outside the ordinary course of business or not on ordinary market terms.
Under the SMA, a Finnish share issuer admitted to trading on a regulated market must disclose material related-party transactions no later than when they become binding, including the related party’s name, relationship, timing and value. Financial statements must also disclose material related-party transactions not concluded on normal market terms, subject to statutory exemptions and the requirement to give a true and fair view. The Finnish Corporate Governance Code further expects listed companies to maintain processes for identifying and evaluating related-party transactions.
3. Shareholder Rights and Agreements
3.1 Shareholder Rights
The Companies Act governs shareholder rights, which shareholders exercise at the general meeting. Every shareholder has the right to attend, including holders of non-voting shares unless the articles of association state otherwise. Any shareholder may put a matter on the agenda of the general meeting. As a rule, each share grants one vote, but the articles of association may provide shares with different or non-voting rights.
Most decisions require a simple majority of votes cast. Certain decisions may, however, according to the Companies Act, require a two-thirds majority of both the votes cast and the shares represented. Shareholders have the right to request detailed information on circumstances that may affect the evaluation of the financial statements or of a matter dealt with by the meeting.
Minority rights, typically exercisable by shareholders holding at least one-tenth of all shares, include the rights to:
- demand an extraordinary general meeting;
- postpone the approval of the financial statements to a continuation meeting;
- demand a minority dividend (at least half of the profit for the financial period, but not more than 8% of equity);
- apply for a special audit; and
- bring an action in their own name on behalf of the company against directors, the managing director or another shareholder, provided the company is unlikely to pursue the claim itself.
The derivative action is also available irrespective of shareholding where non-enforcement would breach the principle of equal treatment.
A decision of the general meeting may be challenged by an action of objection within three months of the decision; otherwise, it is deemed valid. That time limit does not apply to void decisions, except that an action relating to a merger or demerger decision may not be brought more than six months after its registration.
A decision is void if:
- no notice of the meeting was delivered or the notice provisions were materially breached;
- a required shareholder consent under Chapter 5, Section 29 was not obtained;
- the decision is clearly contrary to the principle of equal treatment and the affected shareholder has not consented; or
- the decision could not lawfully have been made even with the consent of all shareholders.
3.2 Shareholder Agreements
Shareholders’ Agreements
Shareholders’ agreements supplement the Companies Act and the articles of association. The Supreme Court (Korkein oikeus – KKO) has described them as agreements between shareholders on how they act as shareholders and as members of company bodies. They are enforceable under general contract law between the parties but cannot override mandatory company law. The company is bound only if it is a party. Typical provisions include:
- reserved matters requiring unanimity or qualified majority;
- board composition;
- financing;
- transfer restrictions and pre-emption rights;
- tag-along and drag-along rights;
- call and put options;
- leaver provisions;
- deadlock mechanisms;
- valuation;
- dispute resolution; and
- sanctions for breach such as damages and contractual penalties.
Restrictions on transfer may be included in the articles only as a redemption clause or a consent clause. A redemption clause in the articles has effect against the acquirer, who has no shareholder rights until it is determined whether the right is exercised, apart from the right to distributions and to pre-emption in share issues. A contractual right of first refusal, by contrast, binds only the contracting shareholder.
A shareholders’ agreement may also not replace consents required by the Act. In KKO 2020:34, an offer obligation in the agreement did not amount to the shareholder’s consent required for a directed redemption. An arbitration clause in the agreement binds only its parties unless its scope is expressly extended. The agreement and the articles should therefore be co-ordinated.
Legal Mechanism and Remedies
Finnish law has no general unfair prejudice or oppression remedy. Minority protection instead rests on the principle of equal treatment and on specific statutory remedies, alongside contractual remedies under the shareholders’ agreement. A shareholder may challenge general meeting decisions through an action of objection or an action to declare a decision void. Board members, the managing director and shareholders who have intentionally or through negligence caused damage to the company intentionally or negligently, and shareholders for damage caused by intentionally or negligently contributing to a breach of the Companies Act or the articles of association, may be liable for damage caused to the company.
Shareholders holding at least one-tenth of the shares, or who show that non-enforcement would breach equal treatment, may pursue a derivative action in their own name if the company is unlikely to do so. A shareholder may also apply for a special audit. A shareholder holding more than nine-tenths of the shares and votes has a squeeze-out right, and the minority a corresponding sell-out right.
Where a shareholder has intentionally abused their influence, the court may order that shareholder to redeem the other shareholder’s shares at a fair price, assessed as if there had been no abuse.
As a last resort, the court may order liquidation or deregistration of the company. An arbitration clause in the articles binds the company, shareholders and management. Partnership disputes are governed by the Partnerships Act (389/1988), which provides for termination, withdrawal and court-ordered liquidation.
4. Mergers and Acquisitions
4.1 Legal Framework
The Companies Act governs, among other matters, corporate mergers, demergers and provisions relevant to share acquisitions of limited liability companies. The SMA regulates takeover bids, disclosure obligations and capital markets activities for listed companies. In addition, the Competition Act (948/2011) is relevant to mergers, as it contains the rules on merger control together with authorities such as the Finnish Competition and Consumer Authority (FCCA).
As limited liability companies are the most common form of business entity in Finland, the most common deal structures are share acquisitions (private companies), public tender offers (listed companies), statutory mergers and asset deals. Key structuring considerations depend on, among other things:
- ownership concentration;
- target listing status;
- liabilities to be assumed;
- creditor protection;
- tax;
- merger control;
- foreign-investment approvals; or
- other approvals.
The most recent change to Finnish public M&A regulation is the amendment to the SMA (163/2024), which extended the mandatory takeover bid and flagging obligations to companies whose shares are traded on a multilateral trading facility (MTF). A recent court decision of note is KKO 2025:94, which concerns determination of the redemption price in minority squeeze-out proceedings under Chapter 18 of the Companies Act. The decision clarifies the valuation principles applicable when special reasons exist to deviate from the tender offer price presumption set out in Chapter 18, Section 7, Subsection 3 of the Companies Act.
5. Capital Markets
5.1 Securities Regulation and Public Offerings
Finnish securities market regulation is highly harmonised with EU law. The key legislation consists of the Prospectus Regulation (EU) 2017/1129, as amended by the Listing Act (Regulation (EU) 2024/2809), MAR and the SMA. Listed companies are also subject to the rules of Nasdaq Helsinki Ltd, which operates the regulated market (the Helsinki Stock Exchange) and the Nasdaq First North Growth Market Finland (an MTF). The national competent authority overseeing capital markets is the Finnish Financial Supervisory Authority (FIN-FSA).
Public offerings are governed by Chapter 3 of the SMA and the Prospectus Regulation, supplemented by Nasdaq Helsinki’s issuer rules. A FIN-FSA-approved prospectus is generally required for a public offer of securities or for admission to trading on the regulated market, unless an exemption applies. After listing, issuers must comply with MAR inside-information rules, periodic financial reporting and trading-venue disclosure rules, while shareholders and comparable persons are subject to separate major-holding notification obligations.
The FIN-FSA scrutiny period is generally ten working days, extended to 20 working days for certain first-time issuers and reduced to seven working days for qualifying EU Follow-on prospectuses under the Listing Act regime. The overall IPO process typically takes several months.
Stock exchange listing requirements operate alongside Finnish and EU securities regulation. For a regulated-market listing, the issuer must satisfy Nasdaq Helsinki’s admission requirements, while any required prospectus is approved separately by the FIN-FSA. Nasdaq Helsinki’s rules also impose continuing issuer obligations that complement statutory disclosure requirements. For Nasdaq First North Growth Market Finland, admission is typically based on a company description under the MTF rules, but a prospectus must be prepared where the Prospectus Regulation or national law requires one, including in connection with a public offer.
Prospectus exemptions must be assessed separately for the public offer and for admission to trading. The main public-offer exemptions include offers below the national prospectus threshold, which from 5 June 2026 is generally:
- EUR12 million over 12 months without passporting;
- offers addressed solely to qualified investors;
- offers addressed to fewer than 150 non-qualified investors per member state; and
- offers where the denomination or consideration is at least EUR100,000.
The Listing Act also introduced exemptions for certain follow-on issuances of fungible securities by listed issuers, provided the relevant conditions are met and a short information document is filed with the competent authority and made available to the public. Under the SMA, a basic information document is generally required for public offers that reach EUR1 million over 12 months but remain below the prospectus threshold.
Finland does not impose a separate statutory hold period on securities distributed under a prospectus exemption. Each resale is assessed as a separate offer under Article 5 of the Prospectus Regulation and may require a prospectus if it constitutes a public offer and no exemption applies; a further prospectus is not required where a valid one remains available with the responsible person’s written consent.
Non-equity securities admitted to a qualified-investor-only market segment may not be resold to non-qualified investors without a prospectus. Non-compliance may lead to FIN-FSA action, including suspension or prohibition of the offer, public notice and administrative sanctions.
5.2 Continuous Disclosure
Listed companies in Finland whose securities are admitted to trading on a regulated market or an MTF are subject to ongoing and periodic disclosure obligations under MAR, the SMA and the rules of the relevant trading venue. The ongoing disclosure regime centres on inside information, which must generally be disclosed as soon as possible, subject to MAR rules on delayed disclosure and protracted processes. It also includes disclosure of managers’ transactions and transactions by closely associated persons. Periodic reporting includes annual financial statements, the management report and half-yearly reporting; First North requirements are generally lighter than those for the main market.
Material events, including significant transactions and material changes in outlook, are normally disclosed through a stock exchange release, or a company release for First North issuers, via Nasdaq Helsinki and the issuer’s official disclosure channels. The release is also made available on the issuer’s website. Delayed disclosure is permitted only where the conditions under MAR are met, and the FIN-FSA must be notified after disclosure where required.
5.3 Insider Trading
Market abuse in Finland is primarily governed by MAR, which prohibits insider dealing, unlawful disclosure of inside information and market manipulation. These prohibitions are supplemented at the national level by the SMA and, as regards criminal liability, by Chapter 51 of the Finnish Criminal Code (39/1889), which transposes the EU Directive on criminal sanctions for market abuse (2014/57/EU).
The FIN-FSA supervises compliance and may obtain information and documents, conduct inspections and hear representatives of supervised entities and other market participants. It may impose administrative fines, public warnings and penalty payments. Serious suspected offences are referred to the police. Criminal sanctions include fines or imprisonment of up to two years, or up to four years for aggravated offences.
5.4 Shareholder Disclosure
In Finland, disclosure of substantial shareholdings, or flagging, is governed mainly by Chapter 9 of the SMA, which implements and supplements the Transparency Directive regime. Following amendments that entered into force on 19 April 2024, the obligation also applies to Finnish companies admitted to trading on Nasdaq First North Growth Market Finland, subject to the transition rules that applied in 2024.
Shareholders and persons comparable to shareholders must notify both the issuer and the FIN-FSA when a relevant holding or voting-right threshold is reached, exceeded or falls below. The issuer itself must also disclose threshold crossings resulting from transfers, acquisitions or annulments of its own shares.
The thresholds are 5%, 10%, 15%, 20%, 25%, 30%, 50%, ⅔ and 90% of the total votes or shares. The obligation covers direct and indirect holdings, controlled entities and chains of control. It also captures financial instruments that entitle the holder to acquire shares or create an equivalent long economic position, whether physically or cash settled.
Failure to comply with the flagging obligation may result in administrative sanctions imposed by the FIN-FSA, including administrative fines. A flagging notification must be made in writing without undue delay and no later than the trading day following the date on which the shareholder became aware, or should have become aware, of the transaction or other event triggering the obligation. In practice, investors close to a threshold should monitor aggregated direct and indirect holdings, voting rights and relevant financial instruments in advance, as late notifications may attract regulatory scrutiny.
5.5 Internal Controls and Whistle-Blower Regimes
The statutory baseline for corporate compliance in Finland is set by company-specific laws, such as the Companies Act and the Co-operatives Act (421/2013), which impose responsibility on the board of directors to oversee the administration of the company, including the appropriate organisation of its operations. In a listed company, the board’s monitoring responsibility extends to the company’s financial reporting system, internal control and auditing, as well as risk management systems. Additionally, the board of directors is responsible for monitoring the audit of the company.
Entities such as limited liability companies and co-operatives are required to establish an internal reporting channel for reporting information on breaches of legislation if the company regularly has at least 50 people employed. The person responsible for handling a report must investigate the accuracy of the report and, where necessary, act in the event of a breach.
The reporting person shall be protected against any form of retaliation by their employer as a result of the reporting of infringements. Obliged entities under the Act on Preventing Money Laundering and Terrorist Financing (444/2017) are also required to allow their employees to report any suspected violation of the Act in accordance with whistle-blowing procedures.
For listed companies, further recommendations regarding corporate governance and internal control are presented in the Finnish Corporate Governance Code.
6. Secured Transactions
6.1 Transaction Financing and Security Interests
Secured Transactions Law
Finnish secured transactions law is not codified in a single security code and does not provide for a single all-assets security instrument comparable to a common-law debenture; instead, security is based on asset-specific legislation and general principles of pledge law.
The main forms of security in commercial financings are share pledges, receivables pledges, bank account pledges, real estate mortgages and business mortgages, the latter sometimes being described as Finnish floating charges over qualifying movable assets. Security may also be taken over certain other assets, such as registered intellectual property (IP) rights, vessels, aircraft and certain vehicles, where relevant.
Financial collateral arrangements may benefit from a separate regime under the Finnish Act on Financial Collateral Arrangements (11/2004), implementing Directive 2002/47/EC, provided that the parties, secured obligations and collateral fall within the statutory scope.
Perfection Requirements
Perfection requirements are asset-specific. Real estate mortgages and business mortgages are registered security interests, while pledges over receivables, bank accounts and shares are generally perfected through notice, blocking or control arrangements, delivery of certificates or entries in the relevant book-entry, shareholder or other register, depending on the asset.
Priority is primarily determined by the type of security, the timing and effectiveness of perfection and mandatory statutory ranking rules. A business mortgage is an important exception to a simple priority analysis: in bankruptcy, it gives priority only to 50% of the value of the mortgaged assets after certain higher-ranking claims have been paid, with the balance ranking as an ordinary claim. Enforcement is generally available, but insolvency and restructuring proceedings, mandatory priority rules and claw-back rules may affect timing, process and recoveries.
Acquisition Financings
Finnish acquisition financings are structured by reference to the assets, obligors and lenders involved; where Finnish-law security is required, it is typically taken over identified Finnish assets rather than through a single all-assets security instrument. A typical Finnish security package includes share pledges, bank account pledges, receivables pledges and business mortgages, with real estate or other asset-specific security added where material.
Guarantees and security granted by Finnish companies within the acquisition structure must be assessed separately under the Companies Act, in particular against the prohibition on providing funds, loans or security to enable a third party to acquire shares in the company or its parent, and against corporate benefit, solvency, shareholder equality and unlawful distribution rules. In multi-lender financings, intercreditor arrangements and security agency provisions are commonly used to regulate contractual ranking, enforcement control and proceeds waterfalls, subject always to Finnish perfection requirements and mandatory insolvency priority rules.
Secured Finance Reform
No recent Finnish secured finance reform appears to have required a wholesale change to standard loan or security documentation. Financing practice has instead been shaped mainly by market conditions, including higher interest rates, more conservative credit processes, tighter covenants and the increased role of private credit in acquisition finance.
EU-level banking and insolvency developments, including the restructuring and insolvency framework and prudential reforms, as well as sector-specific Finnish regulation such as covered bond and mortgage bank rules, should still be monitored where relevant. These developments have generally affected structuring, diligence and negotiation practice more than the basic Finnish security package itself.
7. Commercial Contracts
7.1 Contract Formation and Enforceability
Finnish contract law rests on the principle of contractual freedom. A binding contract arises from a matching offer and acceptance (or other expression of mutual consent); consideration is not required. The principal statutes are the Contracts Act (228/1929), the Sale of Goods Act (355/1987), the Consumer Protection Act (38/1978) and the Code of Real Estate (540/1995). Further sector-specific legislation supplements these in areas such as insurance, construction and financial services.
Finland has ratified the United Nations Convention on Contracts for the International Sale of Goods (CISG), but declared it inapplicable to sales between Nordic countries. Finnish law does not impose general formal requirements for contract validity, meaning both oral and written agreements are enforceable. Notable exceptions include the sale of real estate, which under the Code of Real Estate must be in writing, signed and authenticated by a public purchase witness unless completed digitally in the official e-Property Commerce Service, where no purchase witness is required.
The Contracts Act sets out the principal grounds for invalidity, including duress, fraud, exploitation, unconscionable bargain, mistakes or transmission errors in declaration of intent or if the agreement contravenes honour and good faith. A contract or term may also be invalid if it contravenes mandatory law or public policy. Section 36 permits courts to adjust or set aside contract terms leading to unfair results, though this is rarely applied between B2B parties of comparable bargaining power and carries greater weight in consumer and employment contexts.
Finnish contract law places substantial weight on good faith and fair dealing. Interpretation is holistic, considering not only the contract text but also pre-contractual negotiations, the parties’ intentions and loyalty duties. The law also recognises culpa in contrahendo, pre-contractual liability for blameworthy conduct during negotiations, and a party may be liable even without a concluded contract if negotiations are broken off in bad faith after the other party reasonably relied on agreement. Contractual limitation of liability is permitted but subject to the Section 36 reasonableness test and to mandatory liability rules in sector-specific legislation.
7.2 Termination and Remedies
Finland has no general code of obligations, but remedies for breach of contract are codified in detail in sector-specific legislation, principally the Sale of Goods Act, the Consumer Protection Act and the Code of Real Estate, and are supplemented by established uncodified general principles of contract law.
There is no general statutory regime for force majeure or hardship. The doctrine is addressed through sector-specific legislation, most notably the Sale of Goods Act, which exempts a party from liability for damages where the delay or defect is attributable to an impediment beyond the party’s control. Crucially, force majeure operates principally to relieve a party from liability for damages; it does not extinguish the underlying obligation to perform.
Finnish law distinguishes between termination by notice (irtisanominen) and cancellation (purkaminen) in case of material breach, which may trigger restitution of performances already rendered. Pursuant to established Supreme Court jurisprudence (KKO 2019:13), even long-term contracts of indefinite duration may, as a rule, be terminated by notice, irrespective of whether the contract contains an express termination clause. The essential requirement is that the terminating party must give reasonable consideration to the interests of the counterparty.
Wrongful termination gives rise to damages under general tort law principles. The standard is full compensation: the injured party is restored to the financial position it would have occupied had the contract been performed. Indirect losses are recoverable only where the breach is attributable to negligence.
7.3 Intellectual Property in Commercial Transactions
Key IP issues in commercial agreements include:
- ownership of background IP, newly created IP and improvements;
- licence scope (permitted use, territory, exclusivity, duration);
- confidentiality and trade secret protection, including post-termination handling;
- assignments of rights and registrations; and
- warranties, liability allocation and IP infringement protection.
The employer’s right to acquire the invention depends on the connection between the invention and the employment. The employee is entitled to reasonable compensation whenever the employer acquires rights in the invention, even if a prior agreement purports to exclude compensation. Regarding copyright, there is no general statutory transfer to the employer with the exception of computer programs and databases, but the employer gains a right of use. For commissioned works, Finnish copyright law provides no automatic transfer to the commissioning party; the creator retains copyright unless contractual assignment is agreed.
Ownership of jointly developed inventions is typically governed by the joint development agreement between the parties. Finnish patent law follows the general principle that the inventor is the initial right-holder, and any transfer must be agreed upon contractually.
Finnish law currently has no established jurisprudence addressing copyright protection and AI-generated works. As an AI system cannot qualify as a natural person under the Copyright Act, output generated with limited human involvement is unlikely to qualify for copyright protection.
Civil disputes concerning patents, trade marks, copyright, registered designs and utility models are heard by the Market Court. IP infringement remedies include court-issued injunctions prohibiting continued infringement, reasonable compensation (even without fault), full damages for intentional or negligent infringement, destruction or alteration of infringing goods, publication of judgments, criminal sanctions under the Criminal Code (39/1889) (prosecuted before the Helsinki District Court), precautionary evidence preservation measures, right-to-information orders and customs detention of suspected infringing goods.
7.4 Consumer Protection
The principal statute is the Consumer Protection Act (38/1978), a general law governing marketing, contract terms, adjustment of agreements and consumer sales. It applies to the supply, sale and marketing of consumer goods and services from traders to consumers. Key provisions include a 14-day cooling-off period for off-premises selling and distance selling (ie, e-commerce), pre-contractual disclosure requirements on product characteristics, total price, delivery terms and cancellation rights, and a prohibition on contractual terms that, taking account of price and other relevant aspects, are to be regarded as unfair to consumers. EU directives, including the Unfair Commercial Practices Directive (2005/29/EC) and the Consumer Rights Directive (2011/83/EU), are implemented through the Act.
A practice is unfair if it contravenes generally acceptable business practice and materially impairs the consumer’s informed decision-making. Misleading advertising – false or deceptive information in marketing or customer relationships – is assessed against the average consumer standard (reasonably informed and attentive, per CJEU case law). The Consumer Protection Act also prohibits aggressive practices, assessed by reference to the timing, location, nature, language, behaviour, persistence and exploitation of consumer vulnerability.
The Consumer Ombudsman operating within the FCCA enforces compliance through prohibitory injunctions (with conditional fines), Market Court proceedings and penalty fees of up to 4% of annual turnover under the Act on Certain Powers of the Consumer Protection Authorities (566/2020). The Consumer Ombudsman may also intervene in unlawful online content, including ordering content removal or blocking access. Individual consumer disputes are handled through the Consumer Disputes Board. Consumers may claim a price reduction where an unfair or misleading practice influenced their purchase, and traders are liable in damages for intentional or negligent violations.
8. Foreign Investment
8.1 Competition and Merger Control
Merger control in Finland is governed by the Competition Act (948/2011) and enforced by the FCCA. Special rules on corporate acquisitions affecting defence, security or critical national interests apply under the Act on the Screening of Foreign Corporate Acquisitions (172/2012).
A concentration must be notified to the FCCA where the parties’ combined turnover in Finland exceeds EUR100 million and at least two parties each exceed EUR10 million. Under the one-stop-shop principle, Finnish rules do not apply where the EU Merger Regulation (Council Regulation (EC) No 139/2004 – EUMR) thresholds are met, unless a referral mechanism is invoked. Notification must be filed before implementation, either after the agreement is concluded (or a public bid announced), or earlier once the parties can demonstrate with sufficient certainty their intent to conclude the concentration.
The FCCA has 23 working days (Phase I) for its initial assessment. If the concentration may significantly impede effective competition, a Phase II investigation of up to 69 working days follows (extendable by the Finnish Market Court by up to 46 working days). The substantive test is whether the concentration may significantly impede effective competition, in particular by creating or strengthening a dominant position (significant impediment to effective competition – SIEC), corresponding to that applied under the EUMR.
If a concentration is implemented without notification, the Market Court may, on the FCCA’s proposal, prohibit or order the dissolution of the concentration, or impose conditions. Penalty payments of up to 10% of each infringing undertaking’s worldwide total turnover may also be imposed.
Anti-competitive agreements and abuse of dominance are prohibited under Sections 5 and 7 of the Competition Act, corresponding to Articles 101 and 102 of the Treaty on the Functioning of the European Union (TFEU). The FCCA may require cessation of an infringement and impose behavioural remedies; structural remedies may be imposed by the Market Court on the FCCA’s proposal. The FCCA may also accept binding commitments eliminating the anti-competitive conduct. Penalty payments may not exceed 10% of worldwide turnover. Private damages claims are available under the Act on Compensation of Damages Related to the Infringement of Competition Law (1077/2016).
8.2 Foreign Investment Restrictions and Sector-Specific Rules
Foreign corporate acquisitions are screened under the Finnish FDI Act. Screening covers defence, security and other sectors critical to vital societal functions. The obligation is triggered when a foreign buyer acquires at least one-tenth, ⅓ or ½ of voting rights (or corresponding actual influence) in a Finnish target.
Defence and security acquisitions require mandatory pre-closing approval from the Ministry of Economic Affairs and Employment (MEAE); for other critical sectors, notification is voluntary. No statutory time limits apply to defence/security transactions. For other critical interests, MEAE has six weeks for initial review and three months for further review before potential Council of State referral; inaction within these periods results in deemed approval. No filing fees apply. Failure to apply, failure to disclose information, or the provision of false information may be punished by a fine under Section 10 of the Finnish FDI Act.
Finland imposes no general prohibition on foreign ownership, but several sector-specific restrictions apply:
- financial services require authorisation from the FIN-FSA, with control changes subject to regulatory approval;
- real estate acquisitions require a Ministry of Defence permit under the Act on Transfers of Real Estate Requiring Special Permission (470/2019, as amended); and
- energy grid operations require a licence from the Finnish Energy Authority.
Regarding FDI screening, the defence sector faces the strictest requirements: “foreign buyer” includes all non-Finnish persons – including EU/European Free Trade Association (EFTA) nationals – whereas in other critical sectors only non-EU/EFTA interests are captured.
The Finnish FDI Act serves as Finland’s national security review mechanism. The MEAE confirms an acquisition unless it may jeopardise a key national interest, including military defence, functions vital to society, national security, foreign and security policy objectives, and public order. Where such a risk is identified, the MEAE shall refer the matter to the Council of State, which may refuse confirmation. The MEAE may also impose conditions on approval to safeguard key national interests.
Finland does not maintain incentive programmes specifically targeting foreign investors; domestic and foreign investors are treated equally. In September 2026, the government proposed reducing the corporate income tax rate from 20% to 18% and extending the business loss deduction period from ten to 25 years. Grants are available through Business Finland, ELY Centres and Finnvera. Finland has no free trade or special economic zones, but regional state aid (up to 20% intensity) applies in designated areas until 2027 (Commission decision SA.114318).
The most significant development is the ongoing overhaul of Finland’s FDI screening regime. The Finnish FDI Act was amended in 2014 (496/2014) to expand entity definitions and in 2020 (682/2020) to implement the EU FDI Screening Regulation (2019/452). In June 2026, the MEAE published a draft proposal for a new FDI Act that would extend mandatory pre-closing approval to all non-Finnish investors (including EU/EFTA), cover greenfield investments in specified sectors, add new thresholds (66.6% and 90%), and transfer Phase I review to the National Emergency Supply Agency, with the MEAE retaining Phase II responsibility. The new Act is intended to enter into force in spring 2027.
9. Regulatory Compliance
9.1 Privacy and Data Protection
Finland applies the General Data Protection Regulation (Regulation (EU) 2016/679) (GDPR), specified nationally by the Data Protection Act (tietosuojalaki). In addition, sector-specific laws complement the GDPR in areas such as law enforcement (Act 1054/2018), electronic communications (Act 917/2014), employment privacy (Act 759/2004), health and social welfare (eg, Acts 785/1992 and 703/2023) and the financial sector (eg, the Credit Information Act, 527/2007).
Key compliance obligations include:
- identifying a lawful basis for processing;
- establishing deletion and retention periods;
- providing transparent information to data subjects;
- enabling data subject rights;
- restricting the processing of special categories of data;
- implementing appropriate technical and organisational security measures;
- conducting dataprotectionimpactassessments (DPIAs) for high-risk processing;
- appointing a data protection officer (DPO) where required;
- managing third-party processing;
- reporting data breaches; and
- maintaining records of processing activities.
In the event of a data breach, unless the breach is unlikely to pose a risk, the controller must notify the Data Protection Ombudsman without undue delay and within 72 hours (giving reasons if late), and processors must alert the controller without undue delay. Where the breach poses a high risk to individuals’ rights and freedoms, the controller must also inform affected data subjects without undue delay.
Finland imposes no general localisation requirement for personal data; transfers outside the EEA are permitted subject to GDPR Chapter V safeguards (adequacy decision, SCCs or BCRs, and a transfer impact assessment). Within the Union the GDPR ensures the free movement of personal data. However, public contracting authorities and private companies may impose EU/EEA processing conditions in individual tenders and contracts.
9.2 Anti-Money Laundering, Sanctions and Corruption
The principal anti-money laundering and counter-terrorist financing obligations in Finland are set out in the Act on Preventing Money Laundering and Terrorist Financing (444/2017) (the “AML Act”). These obligations include carrying out customer due diligence measures and assessing the money laundering and terrorist financing risks in the customer relationships. When establishing a permanent customer relationship, obliged entities are required to identify their customers and verify their identities. The obliged entities must also identify the customers’ beneficial owners.
Financial institutions, account operators, insurance or credit intermediaries, gambling operators, auditors, attorneys-at-law and others providing legal or financial services are among the obliged entities under the AML Act. These entities are required to report any suspicious transactions to the Financial Intelligence Unit.
The AML Act also requires compliance with financial sanctions under the Act on the Fulfilment of Certain Obligations of Finland as a Member of the United Nations and of the European Union (659/1967), as well as decisions to freeze funds under the Act on the Freezing of Funds with a View to Combating Terrorism (325/2013).
Supervisory authorities designated under the AML Act may impose administrative sanctions on legal and natural persons for failure to comply with AML requirements or sanctions-related obligations. Available sanctions are administrative fines, public warnings and penalty payments. Non-compliance may also result in criminal penalties.
The primary anti-corruption and anti-bribery obligations applicable to businesses in Finland are found in the Criminal Code (39/1889). The Criminal Code prohibits bribery both in business and against public authorities. Companies typically mitigate corruption risk through compliance programmes encompassing anti-corruption policies, risk assessments, whistleblowing mechanisms, internal supervision and employee training.
Several Finnish authorities co-operate in combating corruption. These include the National Bureau of Investigation (NBI), a national unit of the Finnish Police investigating corruption and bribery offences. Bribery offences may result in a fine or imprisonment under the Criminal Code.
9.3 Environmental, Health and Safety, and Industry-Specific Regulation
Transactions are shaped by the Environmental Protection Act (527/2014), requiring environmental permits for activities that pose a risk of environmental pollution. The Åland Islands have their own environmental legislation. The Finnish legislation imposes strict liability for environmental damage under the polluter pays principle, making environmental due diligence a common practice in M&A transactions. Carbon pricing is managed through the EU Emissions Trading System and a national carbon tax included in the fuel tax.
Finland faces several key challenges in climate-related litigation and corporate environmental liability. Because Finnish law operates mainly through environmental permitting and strict liability for environmental damage, the main obstacles are establishing causation, demonstrating standing and attributing responsibility. Although the Act on Compensation for Environmental Damage (737/1994) requires only that the causal link between the activity and the damage be shown to be probable, even this threshold may be difficult to meet in climate-related cases.
Health and safety obligations derive primarily from the Occupational Safety and Health Act (738/2002) and from the Government Decrees. In Finland, employers must ensure that employees are properly instructed on their work, working conditions, equipment, and safe working practices, including any significant changes to work processes. They must also monitor workplace safety and address non-compliance with safety instructions. High-risk work requires a specific risk assessment.
The Occupational Safety and Health Administration supervises compliance with occupational safety and health legislation. Failure to comply may result in criminal liability for the employer or its representatives under the Criminal Code.
Finland allows most businesses to operate freely after registration in the Trade Register and Tax Administration registers. Corporations from outside the EEA establishing a branch in Finland, and natural persons with a place of residence outside the EEA, are required to obtain a licence granted by the Finnish Patent and Registration Office to engage in business activities. Specific industries – providing, for example, alcoholic beverages, pharmaceuticals, financial services, energy and transport – require additional licences from dedicated authorities.
9.4 Artificial Intelligence
The EU AI Act (Regulation (EU) 2024/1689) is directly applicable in Finland (1377/2025), supplemented by Finnish national legislation on supervision and enforcement. Regulations such as Finnish non-discrimination and data protection legislation apply to organisations deploying AI systems in Finland. Following the AI Omnibus simplification (Regulation (EU) 2026/1744), the rules for high-risk AI systems in sensitive areas (under Annex III) apply from 2 December 2027, and for those embedded in regulated products (under Annex I) from 2 August 2028.
Under the AI Act, transparency obligations for providers and deployers apply depending on the AI system’s function and use, while the GDPR mandates meaningful information about automated decision-making logic. Bias is addressed through data-governance requirements (relevant, representative data) for high-risk AI. Accountability is ensured via designated sector-specific national supervisory authorities, human oversight requirements and substantial penalties for non-compliance.
9.5 Other Regulatory Compliance Requirements
In Finland, businesses must adhere to the Finnish Accounting Act (1336/1997) and applicable standards issued by the Accounting Board. Financial statements must give a true and fair view of the company’s financial position and results of operations. Furthermore, listed companies are required to prepare consolidated financial statements in accordance with the International Financial Reporting Standards (IFRS). Compliance with the Accounting Act is supervised by the Finnish Patent and Registration Office and the Financial Supervisory Authority.
10. Employment and Labour
10.1 Employment Standards and Workplace Regulation
The Finnish Employment Contracts Act (55/2001) is the principal statute governing employment relationships. Other key legislation includes the Working Time Act (872/2019), Annual Holidays Act (162/2005) and Co-operation Act (1333/2021). Collective agreements also play a central role by establishing sector-specific minimum employment terms that may supplement statutory provisions.
When terminating an employment relationship, the type of employment contract in question is relevant. Generally, a fixed-term employment contract cannot be terminated before its expiry unless the parties have expressly agreed on the right of early termination.
Termination of an until further notice contract on personal grounds may be justified in situations such as where the employee has seriously breached or neglected obligations or applicable legislation, or where the employee’s ability to perform their work has substantially changed. Before terminating employment, the employer must as a general rule provide support, guidance and a warning, allowing the employee an opportunity to improve. If the termination is based on reduced work capability, the employer must also assess redeployment options.
Financial and production-related terminations require genuine business reasons, an assessment of alternative work or retraining opportunities and objective selection criteria. Employers must ensure that the termination is based on proper reasons.
An unlawful dismissal may result in compensation of between three and 24 months’ salary under Chapter 12, Section 2 of the Employment Contracts Act.
10.2 Executive Compensation and Restrictive Covenants
Executive compensation arrangements in Finland are typically structured through salary and additional forms of compensation, such as cash bonuses, share options and pension arrangements. All of these alternatives require careful tax analysis. Share-based arrangements may also require further consideration depending on the company’s structure, particularly regarding the type of shares offered and the timing of share option grants in light of insider trading regulations.
In general, employees are subject to non-compete during their employment under the Employment Contracts Act. Post-employment non-compete obligations may be agreed upon in an employment contract, subject to the statutory limitations set out in the Employment Contracts Act, which require a particularly weighty reason related to the employer’s operations or the employment relationship, as well as mandatory compensation corresponding to 40–60% of the employee’s salary.
Non-solicitation covenants have in some cases been treated as non-competition covenants when they restrict the employee’s ability to pursue their profession or engage in work within the same field. Confidentiality covenants are enforceable for trade secrets under the Employment Contracts Act and the Trade Secrets Act (595/2018).
11. Real Property and Commercial Leasing
11.1 Requirements for Land Ownership
Land ownership is registered in the Title and Mortgage Register in accordance with the Code of Real Estate (540/1995). The most fundamental form of land ownership in Finland is direct ownership of real estate. Real estate can also be co-owned. Indirect ownership of real estate through limited liability companies is common as well.
There are no general restrictions on the foreign ownership or sale of real estate. However, non-EU/EEA individuals and entities, as well as entities in which a non-EU/EEA individual or entity holds at least one-tenth of the total number of votes or shares, require a mandatory permit from the Ministry of Defence. The Ministry of Defence may prevent real estate transactions involving Russian or Belarusian actors. Furthermore, a land acquisition permit is required to acquire real estate on the Åland Islands for anyone who does not have the Åland right of domicile.
11.2 Commercial Real Estate Transactions
The key legal framework in Finland governing real estate transactions is the Code of Real Estate, which governs ownership transfers, property and mortgage rights. The Real Estate Register Act (392/1985) governs the registration of real estate and other register units in land and water areas. The National Land Survey of Finland maintains the Land Title and Mortgage Register as well as the Real Estate Register, in which ownership rights and encumbrances are publicly recorded.
The Code of Real Estate requires purchase documentation to be in writing and authenticated by a public purchase witness, unless completed through the official e-Property Commerce Service, in which case no witness is required. Ownership changes must be publicly registered. Buyers should also check for real estate mortgages and registered special rights (e.g. leases or usufructs), which bind a third party in good faith once registered. Priority for mortgages is based on the order of registration. The buyer bears the consequences of defects it should have noticed on inspection. The seller is liable for defects in quality, possession and title. Environmental risk (soil contamination, polluter pay regime) is handled through due diligence, warranties and indemnities.
In mortgage financing, real estate mortgages and share pledges over the shares of a real estate holding company play a significant role, as the financing arrangements and tax treatment differ between them. The enforcement of a real estate mortgage requires an enforcement title from a district court (Enforcement Code (705/2007)), after which the security may be enforced through an enforcement officer. The creation or enforcement of a share pledge is not governed by the Code of Real Estate and does not require an enforcement title.
Commercial land leasing is governed by the Land Tenancy Act (258/1966). Key considerations include whether the lease is registrable (for third party protection and bankability), the lease term and renewal options, the transferability of the lease, the right to construct on the property, indexation of lease payment, and the allocation of liability for damages and costs.
Recent Code of Real Estate amendments enable parties to agree on a contractual withdrawal fee in informal real estate agreements, even though the underlying agreement remains non-binding with respect to the real estate transaction itself. The amendments also introduced the possibility of registering leasehold rights to water areas.
DKCO
Köpmansgatan 4
Mariehamn
Finland
Unioninkatu 30
Helsinki
Finland
+358 20 527 4000
info@dkco-law.com www.dkco-law.com
Law and Practice
Authors
DKCO was founded in 1994 and is a boutique business law firm with its head office in Mariehamn on Åland and further offices in Helsinki and Vaasa. Corporate and commercial work is handled by eight to ten lawyers, including four partners, drawn from all three offices. The team advises on shareholder arrangements and corporate governance, commercial contracts, mergers and acquisitions, and transaction structuring and financing, drawing on the firm’s competition, procurement, permitting and disputes practices as mandates require. The lawyers work in Swedish, Finnish and English, which is particularly valuable for Swedish sponsors entering Finland and for Åland-connected structures. Recent work includes advising Stockholm Nordtech Midco AB on its acquisition of FinMeas Oy and acting for Silvestica Forest Finland Oy on land lease negotiations covering over 3,000 hectares of development-phase areas for industrial and renewable energy projects.
