Corporate & Commercial 2026
France
Authors
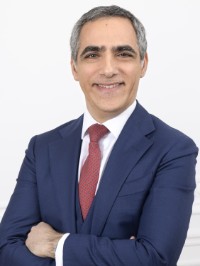
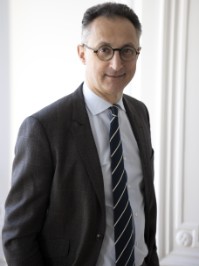
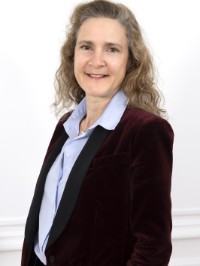
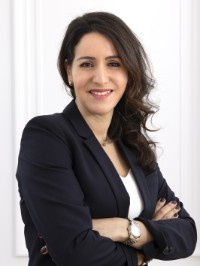
Axipiter is an independent French business law firm with offices in Paris and Lyon and around 30 lawyers. Its Corporate/M&A team advises companies, founders, management teams, family offices and investment funds on governance, acquisitions and disposals, private equity, venture and growth capital, reorganisations and capital-markets matters. The team regularly coordinates cross-border mandates and supports foreign groups establishing or expanding operations in France, as well as French groups expanding abroad. Axipiter combines this transactional practice with employment, corporate and international tax, customs, commercial litigation, competition, intellectual property, data, public business law, environmental, real estate and construction capabilities. Recent work includes advising shareholders on the sale of a French cybersecurity company to an international industrial group, investors on several health-tech, renewable energy and circular-economy financings, founders on disposals to French and European buyers, and corporate groups on acquisitions, reorganisations and French market-entry projects.
1. Business Entities
1.1 Business Organisations
Main Vehicles
French business activity is commonly conducted through a société par actions simplifiée (SAS), société à responsabilité limitée (SARL) or société anonyme (SA). Each has separate legal personality and limited liability, subject to fraud, guarantees and specific director-liability rules. The SAS is the default choice for private M&A, joint ventures and venture or private-equity investments because its articles may allocate governance and economic rights flexibly. It requires at least one shareholder and no statutory minimum capital beyond EUR1.
The SARL is more prescriptive and is often used for closely held or family businesses. Transfers to third parties generally require shareholder approval. The SA is designed for larger businesses and is the usual French form for admission of shares to trading on a regulated market; it has a minimum share capital of EUR37,000 and more formal governance. Other eligible public-company forms include the société en commandite par actions and the European company.
Other structures include the société en nom collectif, whose partners have unlimited joint liability, and civil companies for non-commercial or asset-holding activities. Foreign companies may operate through a branch, which has no separate legal personality, or a subsidiary. Partnerships are generally tax-transparent, whereas companies are normally subject to corporation tax, although elections and special regimes may apply.
1.2 Incorporation and Ongoing Compliance
Incorporation
Founders choose the form, name, registered office, corporate purpose, duration, share capital, financial year and governance, and adopt articles of association. Cash contributions are deposited with an authorised institution; contributions in kind may require an independent contribution auditor, subject to statutory exemptions. The initial directors and, where applicable, statutory auditor are appointed, and foreign directors should check immigration and regulated-activity requirements.
Incorporation is filed electronically through the national business formalities portal. The filing includes the articles, evidence of the registered office and capital deposit, details of officers and beneficial owners, and the publication certificate for the legal notice. The company acquires legal personality upon registration with the Trade and Companies Register and receives national identification numbers. Timing is commonly one to three weeks once a complete file is available, but regulated activities, foreign documents and beneficial-ownership checks may extend it.
Ongoing Compliance
Companies must maintain corporate registers and accounting records, approve annual accounts, allocate profits and file accounts with the registry, subject to confidentiality options for qualifying small businesses. Corporate decisions must comply with the law and articles, and changes are generally filed through the same portal. A statutory auditor is generally required when two of the following three thresholds are exceeded: EUR5 million in total assets, EUR10 million in net turnover, and 50 employees. Group, controlled-subsidiary, public-interest-entity and minority-request rules can require an appointment in other circumstances. Tax, payroll and sector-specific filings apply separately.
1.3 Share Issuances
The subscribed share capital is stated in the articles and divided into shares representing fractions of that capital. France does not use an Anglo-American concept of authorised but unissued capital: new shares require a shareholder decision or a valid delegation to the competent corporate body. The issue price may include a premium above nominal value, but shares cannot be issued below nominal value. An SAS may create ordinary or preference shares carrying tailored voting, dividend, liquidation, conversion or redemption rights, provided mandatory rules and the prohibition on excluding a shareholder entirely from profits or losses are respected. In an SA, statutory rules are more detailed, particularly for listed issuers and multiple-vote or non-voting instruments.
Capital increases are decided by the shareholders under the majority and quorum rules applicable to the relevant form, although authority may be delegated within statutory limits. Existing shareholders of an SA or SAS benefit from preferential subscription rights on cash issues. Those rights may be waived individually or disapplied by the competent shareholder decision, generally on the basis of management and auditor reports.
Changes to class rights require the approvals specified by law and the articles; an SA normally requires a special meeting of the affected class. Private financings also use convertible bonds, bonds with warrants, founders’ warrants and other securities giving access to capital. Corporate approvals, valuation protections, securities-law restrictions and employee incentive tax conditions should be checked together before issuance.
1.4 Distributions and Return of Capital
Dividends and Reserves
Distributions may be made from distributable profit and available reserves after approval of the annual accounts. At least 5% of annual profit, after carried-forward losses, is allocated to the legal reserve until it reaches 10% of share capital. No distribution may reduce net assets below share capital plus non-distributable reserves. Interim dividends require an interim balance sheet certified by a statutory auditor and are capped by the profit shown on that basis. In February 2025, the Cour de cassation also held that profit carried forward from a prior year can be allocated or distributed only by the annual meeting approving the accounts of the following financial year.
Unlawful dividends may be recovered from shareholders who knew, or could not have been unaware, that the distribution was irregular. Directors may incur civil or criminal liability. In a group, upstream distributions also require review of corporate benefit, financial-assistance, tax and insolvency constraints.
Capital Reductions and Buy-Backs
A capital reduction requires an extraordinary shareholder decision and, when it is not motivated by losses, may trigger a creditor-objection period. Equal treatment must be preserved unless all affected shareholders give consent. Private companies may repurchase shares only within statutory mechanisms – eg, a capital reduction, an employee plan or purposes authorised for an SAS. Shares acquired must be cancelled, transferred or otherwise dealt with within the applicable period. Listed issuers may operate buy-back programmes authorised by shareholders and compliant with the EU Market Abuse Regulation, AMF rules and disclosure requirements.
1.5 Control Person Reporting
Beneficial Ownership
Private companies must identify and report their beneficial owners through the business formalities portal and keep the filing current. A beneficial owner is generally an individual who directly or indirectly holds more than 25% of the capital or voting rights, or otherwise exercises control over management or governing bodies. If no individual can be identified, the legal representative is reported under the fallback rule.
Changes in ownership, control or personal details must be filed promptly. Access to beneficial-ownership information is restricted in accordance with EU case law and French rules, but competent authorities, regulated professionals conducting customer due diligence and persons demonstrating a legitimate interest may obtain information within the applicable framework. Incomplete or inaccurate reporting may expose the company and its representatives to fines, management disqualification and registry measures.
Share ownership itself is recorded in the company’s securities accounts for companies limited by shares, or in the articles and registry filings for an SARL. Separate disclosure regimes apply to listed companies, regulated sectors, foreign-investment review and anti-money laundering checks.
2. Corporate Governance
2.1 Legal Framework
Sources and Allocation of Powers
French corporate governance is principally governed by the Civil Code, Commercial Code, Monetary and Financial Code, articles of association and, where relevant, the EU Market Abuse Regulation and listing rules. Certain companies with exclusively public or mixed capital structures are also governed in part by the General Code of Territorial Authorities (notably local public companies and mixed-economy companies). The company’s legal form determines which matters are reserved to shareholders and which belong to management. The articles of an SAS provide broad freedom to design boards, committees, reserved matters and decision procedures, but the president retains statutory authority to represent the company towards third parties.
An SA may use a one-tier board of directors with a chair and chief executive, or a two-tier supervisory board and management board. Public-interest entities and listed issuers face enhanced audit, internal-control, remuneration, gender-balance, sustainability and related-party requirements. The AFEP-MEDEF and Middlenext codes operate on a comply-or-explain basis for issuers that adopt them and strongly influence market practice.
Private companies typically supplement the articles, which are public, with shareholders’ agreements covering board composition, information, vetoes, funding and transfers. Internal limits on management powers are generally ineffective against third parties acting within the corporate purpose, so delegations, signing policies and post-closing governance should be documented operationally as well as contractually.
2.2 Directors’ Duties and Liabilities
Directors and corporate officers must act within their powers, comply with law and the articles and act in the corporate interest, taking into consideration the social and environmental implications of the company’s activities. They owe duties of loyalty, care and confidentiality developed through case law. A parent-appointed director must exercise independent judgement for the company on whose board they sit, even when group interests are relevant.
Civil liability may arise towards the company, shareholders or third parties for breach of law, the articles or mismanagement. A third party generally needs to show a fault separable from the officer’s functions. Shareholders may bring a derivative action on the company’s behalf. Criminal exposure can arise from misuse of corporate assets or powers, inaccurate accounts, unlawful distributions, market abuse, corruption and other offences.
Liability is assessed by reference to each officer’s conduct, although collegiate decisions can expose all participating directors unless dissent is properly recorded. Delegations of authority can transfer operational criminal responsibility when granted to a person with appropriate competence, authority and resources. D&O insurance and indemnities are common, but cannot cover criminal fines or eliminate mandatory liability.
2.3 Board Composition and Independence
Private Companies
An SAS must have a president, who may be an individual or legal entity; all other bodies are optional and defined by the articles. There is no nationality or residence requirement as a matter of general company law, although immigration, tax-residence and regulated-sector rules may matter. A SARL is managed by one or more individual managers. Private companies are not generally required to appoint independent directors.
Public Companies
An SA board ordinarily has three to 18 members, subject to temporary exceptions following a merger. Its articles may require directors to hold shares. Listed companies are expected to include independent directors under the governance code they apply and to establish specialised committees, particularly an audit committee. French law also imposes gender-balance rules for boards of larger companies and employee representation on boards when workforce thresholds are met.
The board determines strategy and monitors implementation; it cannot displace powers reserved to shareholders. Good practice includes a skills matrix, annual conflict declarations, board evaluations, documented information flows, succession planning and executive sessions. Diversity requirements increasingly extend beyond the board to senior-management populations in large companies.
2.4 ESG and Disclosure Obligations
Sustainability Framework
French companies may be subject to sustainability reporting under the EU Corporate Sustainability Reporting Directive (CSRD), as transposed and subsequently amended. The 2026 EU reform reduces the future scope principally to companies exceeding both 1,000 employees and EUR450 million in net turnover, subject to national transposition and transitional rules for financial years beginning before 2027. In-scope companies report under European Sustainability Reporting Standards and obtain limited assurance. Groups should confirm the rules applicable to the relevant financial year, whether a French subsidiary is exempt through consolidated reporting and whether non-EU parent reporting will apply.
Large companies may also be subject to a vigilance plan covering serious human-rights, health and safety and environmental risks arising from their own operations and certain subsidiaries, subcontractors and suppliers. Climate, taxonomy, sustainable-finance and gender-pay disclosures may apply depending on size, activity and listing status. Listed issuers must ensure that sustainability information is consistent with regulated financial and inside-information disclosures.
Boards should map applicable obligations, approve materiality and risk assessments, allocate oversight and maintain auditable data and controls. The corporate interest expressly requires management to consider social and environmental issues, but does not create a general right for stakeholders to direct the company. A société à mission may incorporate a purpose and social or environmental objectives in its articles, with specific monitoring and verification.
2.5 Conflicts of Interest and Related-Party Transactions
Directors should disclose personal interests, abstain where appropriate and ensure that deliberations and minutes demonstrate an informed decision in the company’s interest. The statutory framework is supplemented by articles, board rules and governance codes. Undisclosed conflicts may support liability, nullity in limited circumstances and reputational or regulatory consequences.
Regulated-agreement procedures apply to transactions between a company and specified officers, shareholders or related entities. In an SA, prior board approval is generally required, followed by a statutory auditor’s special report and a shareholder vote. In an SAS, the procedure is usually post-completion reporting and shareholder review, subject to the articles and exceptions for ordinary-course transactions on arm’s-length terms. A SARL has a comparable statutory process.
Group transactions require particular attention to corporate benefit, pricing, cash pooling, guarantees and financial assistance. French case law permits a group interest to be considered where the entities form a genuine group, the support pursues a common economic policy, and the burden is not disproportionate to the supporting company’s financial capacity or liable to disrupt its financial equilibrium. Listed companies must also comply with market-abuse disclosure and enhanced approval and public-disclosure requirements for material related-party agreements.
3. Shareholder Rights and Agreements
3.1 Shareholder Rights
Statutory and Contractual Rights
Shareholders vote on reserved matters, receive distributions lawfully declared, participate in capital changes and share in liquidation proceeds according to their rights. They are entitled to specified corporate documents before meetings and may ask written questions. Minority thresholds allow shareholders in certain forms to request agenda items, seek appointment of an expert to report on management transactions, call or obtain a court-convened meeting, and bring derivative actions.
Majority decisions may be set aside for abuse where they are contrary to the corporate interest and adopted solely to favour the majority at the minority’s expense. A blocking minority may itself be liable for abusive obstruction when it prevents an essential transaction for the sole purpose of advancing its own interests. Emergency and merits proceedings can provide injunctions, nullity, damages or appointment of a provisional administrator, although courts avoid substituting themselves for corporate bodies.
An SAS offers broad scope to create vetoes, class consents and information rights in the articles. Rights appearing only in a shareholders’ agreement bind its parties but normally do not invalidate a corporate decision taken in breach. Investors therefore place structural governance and transfer restrictions in the articles where enforceability against the company and third parties is important.
3.2 Shareholder Agreements
Typical Provisions
Shareholders’ agreements commonly regulate board representation, reserved matters, business plans, financing, information, anti-dilution, pre-emption, rights of first offer or refusal, lock-ups, permitted transfers, tag-along and drag-along rights, founder vesting, leaver arrangements and exit processes. Private-equity agreements also address management packages, liquidity waterfalls and lender rights.
The agreement must be consistent with mandatory company law and carefully coordinated with the articles. A perpetual agreement, which is not usual, may be terminable on reasonable notice; parties therefore use a fixed duration or objective end date. Transfer undertakings must identify price or a determinable pricing mechanism. Penalty clauses may be reduced or increased by a court if manifestly excessive or derisory.
Remedies include damages, contractual penalties and, where sufficiently precise and legally possible, specific performance. Courts may appoint a provisional administrator in exceptional circumstances or dissolve a company for just cause where serious dissension paralyses it. Forced-transfer promises and drag clauses require particular drafting to secure execution if a party defaults. In February 2025, the Cour de cassation confirmed the validity of an objectively triggered “Russian roulette” or “American” clause whose reciprocal mechanism made the transfer price determinable. Confidentiality and arbitration clauses are common, while listed-company agreements may trigger AMF disclosure and concert-party analysis. Tax, employment and financial-assistance consequences should be reviewed when the agreement confers benefits on managers or commits the company itself.
4. Mergers and Acquisitions
4.1 Legal Framework
Private and Public M&A
Private acquisitions are governed by general contract and company law, with sector rules for employee consultation, merger control, foreign investment, regulated businesses and tax. Share deals are most common, using a signing followed by conditions precedent or a simultaneous signing and closing. Asset deals, contributions, statutory mergers, demergers and universal transfers are used where perimeter, tax or succession considerations favour them.
Public takeovers are governed by the Monetary and Financial Code, AMF General Regulation and EU market-abuse rules. Mandatory offers generally arise when a person, alone or in concert, crosses 30% of capital or voting rights of a company listed on a regulated market, or increases a holding between 30% and 50% by at least 1% in less than 12 months. The AMF reviews offer documentation, timetable, equal treatment and, where required, the independent expert’s fairness analysis.
Execution Points
Transactions commonly use locked-box or completion-account pricing, earn-outs, escrow, bank guarantees or W&I insurance. Before signing, parties assess social and economic committee (CSE) information and consultation, merger control, foreign direct investment (FDI) and sector approvals. For sales completed from 27 July 2026, the Law of 26 May 2026 removed the separate employee information procedure for companies whose CSE exercises the powers applicable at 50 employees and reduced the notice period to one month for other in-scope sales of a business or controlling interest; CSE consultation and other applicable procedures remain transaction-critical. Recent reforms also facilitate cross-border conversions, mergers and divisions within the EU and have modernised listed-company financing and governance. Recent case law reinforces drafting discipline: in February 2025, the Cour de cassation validated an objectively triggered reciprocal buy-sell clause, while its May 2025 decision on interdependent settlement and share-transfer agreements underlined the importance of joining all affected parties to proceedings seeking consequential invalidity or lapse.
5. Capital Markets
5.1 Securities Regulation and Public Offerings
Regulatory Architecture and Offering Process
The AMF supervises issuers, public offers, market conduct and regulated-market disclosure; the Autorité de contrôle prudentiel et de résolution supervises regulated financial institutions. Euronext Paris operates the regulated market, while Euronext Growth and Euronext Access provide multilateral trading venues with lighter admission regimes.
An offer of securities to the public or admission to a regulated market generally requires an EU Prospectus Regulation approved by the AMF, unless an exemption applies. Preparation commonly includes issuer reorganisation, audited financial statements, due diligence, governance work, underwriting documentation and AMF review. Timing varies materially, but a first-time issuer should allow several months. Listing rules operate alongside securities law and impose free-float, financial-history, governance and ongoing obligations appropriate to the chosen venue.
Exemptions include offers solely to qualified investors, to fewer than 150 non-qualified persons per EEA state, with a denomination or minimum consideration of at least EUR100,000 per investor, and certain small offers. In France, since 5 June 2026, public offers below EUR12 million calculated over 12 months are exempt from the prospectus requirement, although an information document and filing may still be required depending on the offer. Securities law does not impose a general private-placement holding period, but contractual lock-ups, market-abuse rules and exemptions relied upon for resale must be respected. Non-compliance can result in AMF sanctions, civil liability and criminal offences.
5.2 Continuous Disclosure
Periodic and Inside Information
Issuers on a regulated market publish annual and half-yearly financial reports within statutory deadlines and provide governance, shareholding, remuneration and sustainability information as applicable. They must ensure equal and effective dissemination through regulated information channels and file information with the AMF. Euronext Growth issuers have a distinct, but still material, reporting framework.
Under the EU Market Abuse Regulation, an issuer must disclose inside information concerning it as soon as possible. Disclosure may be delayed on the issuer’s responsibility when immediate publication would prejudice legitimate interests, delay would not mislead the public, and confidentiality can be maintained. The issuer documents the decision and notifies the AMF after disclosure, as required. Special rules apply to protracted processes and regulated financial institutions.
Transaction teams should establish a disclosure committee, restricted lists, clean teams and a documented leak response. Financial guidance, cyber incidents, litigation, management changes and M&A may be material depending on their price sensitivity. Information published in another context should be consistent with regulated disclosures and made available on the issuer’s website for the required period.
5.3 Insider Trading
Prohibited Conduct
The EU Market Abuse Regulation prohibits insider dealing, recommending or inducing insider dealing, unlawful disclosure of inside information and market manipulation. Inside information is precise, non-public information relating directly or indirectly to an issuer or financial instrument that would be likely to have a significant price effect if made public. Legal persons can be liable alongside individuals.
Issuers and persons acting for them maintain insider lists, notify insiders and preserve records. Persons discharging managerial responsibilities and closely associated persons must report relevant own-account transactions once the annual threshold is reached and generally observe a 30-day closed period before financial reports. Market soundings, buy-backs and stabilisation benefit from specific frameworks when conditions are met.
The AMF may investigate, require documents and data, conduct inspections, cooperate internationally and impose substantial administrative fines and professional bans. Serious conduct may also be referred for criminal prosecution. Companies should use dealing codes, pre-clearance, training, information barriers and escalation procedures, particularly during confidential transactions.
5.4 Shareholder Disclosure
Statutory Thresholds
For issuers admitted to trading on a regulated market, a shareholder must notify the issuer and the AMF when crossing, upward or downward, statutory thresholds of 5%, 10%, 15%, 20%, 25%, 30%, one-third, 50%, two-thirds, 90% or 95% of capital or voting rights. Notification is generally due within four trading days. Holdings are aggregated with specified financial instruments and interests held in concert.
At 10%, 15%, 20% and 25%, the shareholder must also declare its intentions for the following six months, including financing, control and board plans. The issuer’s articles may add thresholds from 0.5% upwards, reported to the issuer under the articles. Separate monthly disclosure by the issuer of total voting rights supports investor calculations.
Late disclosure can suspend voting rights above the unreported threshold, automatically for statutory thresholds and, subject to conditions, at another shareholder’s request for articles-based thresholds. AMF sanctions may also apply. Crossing 30% can trigger a mandatory public offer unless an exemption is granted, so derivatives, concert arrangements and intragroup reorganisations should be analysed before execution.
5.5 Internal Controls and Whistle-Blower Regimes
Controls and Reporting Channels
Listed issuers describe internal control and risk-management arrangements in their governance reporting and maintain systems capable of producing reliable financial and sustainability information. Public-interest entities require an audit committee or equivalent body. Regulated sectors impose additional governance, compliance and fit-and-proper requirements.
The Sapin II framework requires companies meeting the statutory workforce and turnover thresholds, and groups headed in France meeting the consolidated test, to implement an anti-corruption programme. Core measures include a code of conduct, internal reporting channel, risk mapping, third-party due diligence, accounting controls, training, disciplinary measures and internal evaluation. The French Anti-Corruption Agency may review programmes and its sanctions commission may order remediation and impose fines.
Whistle-blower rules protect individuals reporting in good faith and without direct financial consideration facts within the statutory scope. Entities with at least 50 employees generally maintain an internal reporting procedure after consultation with employee representatives. Confidentiality, acknowledgement, feedback, GDPR compliance and anti-retaliation are essential. Groups should coordinate French procedures with global hotlines while preserving local rights, privilege and data-transfer safeguards.
6. Secured Transactions
6.1 Transaction Financing and Security Interests
Security Package
French law recognises pledges over shares, securities accounts, receivables, bank accounts, business assets, inventory and equipment, as well as assignments of receivables by way of security, mortgages over real estate and personal or autonomous guarantees. Choice of security depends on the asset, the obligor and whether the financing qualifies for simplified financial-collateral rules.
Perfection may require a written agreement, registration, account entry, dispossession, notification or control. Security over shares or partnership interests must follow the form, account-entry, notice and, where applicable, registration rules for the relevant instrument; business-asset pledges and mortgages are registered. Priority generally follows the applicable perfection or registration date, subject to statutory preferences. Enforcement routes include judicial sale, contractual appropriation where permitted and court attribution, with insolvency stays and avoidance rules materially affecting recovery.
Acquisition financing commonly combines senior facilities, shareholder instruments and a security package granted at closing or after funds flow. French financial-assistance rules prohibit companies limited by shares, including an SA or SAS, from advancing funds, granting loans or providing security for the acquisition of their own shares; corporate benefit and group-support rules apply to all companies. Intercreditor agreements regulate ranking, turnover, enforcement and standstill. The 2021 security-law reform modernised and consolidated many security interests; transaction documents should use the current statutory forms and publicity registers.
7. Commercial Contracts
7.1 Contract Formation and Enforceability
A contract requires consent, capacity and lawful, certain content; consideration is not a separate French-law requirement. Contracts are generally consensual unless legislation requires writing, notarisation, registration or specific consumer formalities. Electronic signatures and records can satisfy writing requirements if identity and integrity conditions are met.
Negotiations must be conducted in good faith. A party may terminate negotiations, but can be liable for wrongful conduct; damages do not normally include the profits expected from the unmade contract. Parties must disclose information that is decisive for consent when the other party legitimately does not know it, excluding valuation of the performance. Error, fraud, duress, incapacity and unlawful content can cause nullity.
Contracts bind the parties and must be negotiated, formed and performed in good faith. Courts seek the parties’ common intention rather than relying solely on literal wording and interpret standard terms against the party proposing them. In adhesion contracts, a non-negotiable term creating a significant imbalance may be deemed unwritten. Clauses excluding liability cannot neutralise an essential obligation, and liability for fraud or gross misconduct cannot effectively be excluded. Commercial parties should specify hierarchy, entire agreement, notice, evidence and liability mechanics with precision.
7.2 Termination and Remedies
For non-performance, the creditor may suspend its own performance, seek specific performance, obtain a price reduction, terminate the contract and/or claim damages, subject to statutory conditions and proportionality. Contractual notice and cure provisions should be followed. Termination may result from an agreed clause, unilateral notice for sufficiently serious breach or a court order; wrongful termination exposes the terminating party to damages and may leave the contract in force.
Damages ordinarily cover foreseeable direct loss, except in cases of gross or intentional breach. Penalty clauses are enforceable but may be adjusted by a court if manifestly excessive or derisory. Parties often exclude indirect loss and cap liability, with carve-outs for fraud, gross fault, confidentiality, IP, data protection and other negotiated risks.
Force majeure requires an event beyond the debtor’s control that could not reasonably have been foreseen at contracting and whose effects cannot be avoided by appropriate measures. Temporary prevention suspends performance unless delay justifies termination; permanent prevention discharges the affected obligation. Article 1195’s hardship provision permits a party to seek renegotiation when an unforeseeable change makes performance excessively onerous and it did not accept that risk. Commercial contracts commonly exclude or tailor this mechanism.
7.3 Intellectual Property in Commercial Transactions
Ownership and Transfer
Assignments and licences should identify the rights, territory, duration, permitted uses, exclusivity, consideration, warranties and enforcement responsibilities. French copyright assignments must separately specify transferred rights and their scope, destination, territory and duration; assignments of future works are restricted. Trade-mark and patent transfers should be recorded with the INPI to be effective against third parties. Know-how requires robust confidentiality and access controls.
Employee inventions follow a statutory regime distinguishing mission inventions, which belong to the employer with additional remuneration, from other inventions that may be claimed for a fair price. Software created by employees in the course of duties generally vests in the employer, but copyright in other employee or commissioned works does not automatically transfer without a compliant agreement. Joint-development contracts should allocate background IP, results, filing, exploitation and exit rights. Purely AI-generated material may lack human authorship and should not be assumed to attract copyright protection.
Remedies for infringement include interim and final injunctions, preservation and seizure measures, damages, recall or destruction and publication of the judgment; counterfeiting may also be criminal. M&A diligence should verify chain of title, open-source use, contractor assignments, domain names, trade secrets, licences, security interests and change-of-control clauses.
7.4 Consumer Protection
The Consumer Code imposes pre-contract information, transparent pricing, conformity guarantees, controls on unfair terms and specific distance and off-premises selling requirements. Consumers generally have 14 days to withdraw from distance and off-premises contracts, subject to exceptions and formalities. Digital content, digital services and goods with digital elements are subject to dedicated conformity and update obligations.
Terms creating a significant imbalance to the consumer’s detriment may be deemed unfair and unenforceable. Aggressive or misleading commercial practices, hidden advertising, false environmental claims and manipulated online interfaces can trigger enforcement. E-commerce businesses must provide seller identity, ordering steps, payment and delivery information, withdrawal mechanisms and accessible terms on a durable medium.
The Directorate-General for Competition, Consumer Affairs and Fraud Control may investigate, issue injunctions, impose or seek administrative and criminal penalties, and coordinate product recalls. Consumers and approved associations may bring individual or group actions in specified fields. The EU Digital Services Act and platform rules add obligations for online intermediaries. International groups should localise consumer journeys rather than relying solely on a global template.
8. Foreign Investment
8.1 Competition and Merger Control
For transactions notified from 1 September 2026, French notification is mandatory when the parties’ combined worldwide turnover exceeds EUR250 million and at least two parties each generate more than EUR80 million in France, provided the transaction lacks an EU dimension. For retail transactions, the corresponding thresholds are EUR100 million worldwide and EUR20 million of French retail turnover for at least two parties. Specific lower thresholds continue to apply in certain French overseas territories. A concentration includes mergers, acquisitions of sole or joint control and full-function joint ventures.
Transactions must not be implemented before clearance. Phase I is normally 25 working days from a complete filing, extendable in specified circumstances; an in-depth Phase II review is usually 65 working days, subject to suspensions and extensions. The Autorité de la concurrence tests whether the transaction significantly lessens competition, considering unilateral, coordinated, vertical and conglomerate effects and efficiencies. Remedies may be structural or behavioural.
Gun-jumping and failure to notify can attract fines of up to 5% of the notifying company’s French pre-tax turnover for the last closed financial year, increased where relevant by the target’s French turnover, plus remedial orders. Anticompetitive agreements and abuse of dominance are separately prohibited under French and EU law, with corporate fines potentially reaching 10% of worldwide group turnover. Transaction protocols should include information-sharing safeguards, clean teams and conduct-of-business covenants that preserve the target’s independence before clearance.
8.2 Foreign Investment Restrictions and Sector-Specific Rules
Scope of French FDI Review
Prior authorisation from the French Minister for the Economy is required where a foreign investor acquires control of a French entity, acquires all or part of a business line, or, if the investor is established outside the EU or EEA, crosses 25% of the voting rights in an unlisted French entity carrying out a sensitive activity. The investor test follows the chain of control. A separate regime applies when a non-EU/EEA investor crosses 10% of the voting rights in a French listed company carrying out a sensitive activity: the investor makes a prior notification and is exempt from a full authorisation request if the Minister does not object within ten business days.
Sensitive activities include defence, security, critical infrastructure and services, energy, water, transport, communications, public health, food security, certain media and R&D in critical technologies such as cybersecurity, AI, semiconductors and biotechnologies. A prior request may be made to confirm whether the target’s activity is in scope. There is no filing fee. The initial review is 30 business days, followed, where necessary, by a further 45 business days; information requests can affect timing.
Clearance may be unconditional or subject to commitments on governance, information, supply, assets or French capabilities. The Treasury’s 2025 report recorded 418 filings and 167 authorised transactions, 49% with conditions. Failure to obtain approval can lead to suspension, unwinding, injunctions and financial penalties. Sector approvals and EU co-operation may run in parallel. France offers grants, tax credits and investment programmes, but incentives depend on project, location and EU state-aid rules.
9. Regulatory Compliance
9.1 Privacy and Data Protection
Core Data-Protection Obligations
The GDPR, the French Data Protection Act and CNIL guidance govern personal data, alongside sector rules for health, communications, finance, employment and cookies. Controllers need a lawful basis for each purpose, clear information, purpose limitation, data minimisation, accuracy, retention controls and appropriate security. Where consent is relied on, it must be freely given, specific, informed and unambiguous; France sets the age of digital consent at 15, and the CNIL actively enforces cookie consent. Controllers must honour individual rights, maintain processing records, use compliant processor agreements and carry out data-protection impact assessments for likely high-risk processing. Disclosure to third parties requires a lawful basis, transparency and appropriate contractual safeguards.
A personal-data breach must be documented and notified to the CNIL within 72 hours of becoming aware of it, unless it is unlikely to result in a risk to individuals’ rights and freedoms. Affected individuals must be informed without undue delay where the risk is high, subject to exceptions. Administrative fines can reach EUR20 million or 4% of worldwide annual turnover, whichever is higher. The CNIL may also issue warnings, compliance orders with daily penalties, and temporary or permanent processing bans, and often publishes its sanctions. In addition, certain breaches of data-protection rules are criminal offences under Articles 226-16 et seq of the French Criminal Code, punishable by up to five years’ imprisonment and a EUR300,000 fine for individuals (up to five times that amount for legal entities). Data subjects may also claim compensation for material or non-material damage, including through collective actions. The EU Digital Omnibus proposal would raise the notification threshold to high-risk breaches and extend the deadline to 96 hours, but it has not yet been adopted.
Transfers to countries recognised as adequate by the European Commission (such as the UK, Switzerland, Japan, Brazil and, for certified organisations, the US under the Data Privacy Framework, whose validity is currently under appeal before the Court of Justice of the EU) may take place freely. Other transfers outside the EEA require safeguards such as standard contractual clauses or binding corporate rules, together with a transfer impact assessment and supplementary measures where necessary. There is no general data localisation requirement under French law, but specific rules apply in certain areas, such as public archives, classified defence information and tax records. In particular, since the April 2026 implementing decree of Article 31 of the SREN Act, State administrations, their operators and certain public interest groupings must use SecNumCloud-qualified (or equivalent EU-certified) cloud services when hosting particularly sensitive data with private providers. Anyone hosting health data on behalf of a third party must also be HDS-certified (hébergeur de données de santé), and the current HDS framework requires such data to be hosted within the EEA, with transparency on risks of access by third-country authorities. In transactions, parties should diligence lawful datasets, cyber incidents, cookies, AI training data and international flows, and should control personal-data disclosure through minimisation and clean-room protocols.
9.2 Anti-Money Laundering, Sanctions and Corruption
Banks, insurers, investment firms, accountants, lawyers in specified transactions and other regulated professionals must identify customers and beneficial owners, assess risk, monitor relationships, retain records and report suspicions to TRACFIN. Obligations intensify for politically exposed persons, high-risk jurisdictions and opaque structures. Commercial companies outside the regulated perimeter still face banking KYC, beneficial-ownership and criminal money-laundering exposure.
EU and French sanctions impose asset freezes, sector restrictions and trade controls. Businesses should screen counterparties, ownership and control, banks, goods, technology, end-use and destination. Dual-use items are governed by EU export-control rules; defence items and certain sensitive products require separate licences. Contractual sanctions clauses do not replace a documented compliance process.
Sapin II requires qualifying large companies and groups to maintain an anti-corruption programme. Bribery of public or private persons, influence peddling and illegal conflict of interest (to name only the most common offenses) can result in corporate and individual criminal liability, exclusion and reputational harm in addition to the annulment of unlawfully awarded public contracts. The Parquet National Financier, criminal courts, customs, Treasury and AFA have complementary powers. Risk-based third-party diligence, approval controls, gifts and hospitality rules, training, accounting controls and investigations are central to transaction and post-acquisition compliance.
9.3 Environmental, Health and Safety, and Industry-Specific Regulation
Environmental due diligence should identify classified installations, environmental permits and planning permissions, soil and groundwater contamination, waste, emissions, protected sites, climate obligations and historic liabilities. Operators may face administrative remediation orders and civil or criminal liability; landowners can also be exposed in defined circumstances. Share deals preserve entity-level liabilities, while asset deals require analysis of permit transfer (and associated risks) and successor obligations. Carbon pricing principally arises through the EU Emissions Trading System for covered activities.
France’s duty-of-vigilance regime and expanding climate and environmental litigation increase scrutiny of group risk mapping and public statements. Green claims must be substantiated. Employers must protect physical and mental health, assess occupational risks in a written risk-assessment document, implement prevention measures and consult employee representatives. Serious incidents may trigger reporting, inspection and criminal proceedings. Liability arising from the operation of a classified installation extends for 30 years following cessation of operations.
Licensing is sector-specific. Financial services, insurance, healthcare, pharmaceuticals, energy, transport, telecoms, defence, food and public-service activities can require regulator approval for operations or changes of control. Urban-planning and environmental authorisations may condition industrial and real-estate projects. Transaction timetables should therefore include an early regulatory matrix, permit portability review and allocation of remediation and compliance costs.
9.4 Artificial Intelligence
EU and French Framework
The EU AI Act applies directly in France using a risk-based model. Most prohibited practices and AI-literacy duties have applied since February 2025; governance rules and obligations for general-purpose AI models since August 2025; and the general enforcement framework and Article 50 transparency requirements since 2 August 2026. Following the revised implementation timetable, requirements for Annex III high-risk use cases apply from 2 December 2027 and those for high-risk AI embedded in regulated products from 2 August 2028.
Providers and deployers must first classify systems and their role. Depending on the category, obligations include risk management, data governance, technical documentation, logging, human oversight, accuracy, cybersecurity, conformity assessment, registration, incident reporting and transparency to individuals interacting with AI or exposed to synthetic content. Employment, credit, essential services and biometric uses warrant particular care. GDPR, consumer, product-safety, discrimination, employment and IP rules apply in parallel.
Businesses should maintain an AI inventory, procurement clauses, acceptable-use policy and approval process; document training data, testing and human review; and allocate incident and regulatory responsibilities. In M&A, diligence should identify proprietary models, third-party dependencies, data rights, open-source components, prohibited uses and future remediation costs. Enforcement can involve substantial turnover-based fines.
9.5 Other Regulatory Compliance Requirements
Additional Regimes
French businesses must consider competition, consumer, product-safety, cybersecurity, tax, customs, employment and sector regulation alongside corporate law. The EU NIS2 Directive is intended to expand cybersecurity risk-management and incident-reporting duties for essential and important entities, but, as at 3 October 2026, the French transposition legislation has not yet been enacted. Potentially in-scope businesses should nevertheless prepare against the directive and monitor the final French legislation and implementing instruments. The EU Digital Operational Resilience Act applies to much of the financial sector, while the Digital Services Act regulates online intermediaries and platforms.
Supply-chain and product businesses should assess CE marking, product traceability, market surveillance and the EU General Product Safety Regulation. Importers and exporters must classify goods, origin and value and manage VAT and customs records. Public-contract counterparties face procurement, integrity and performance requirements.
The applicable compliance perimeter should be mapped by entity, activity, workforce, turnover, data and geography. Acquirers should convert diligence findings into closing conditions, specific indemnities, remediation plans, governance reporting and integration priorities. A global policy is useful, but French employee consultation, whistle-blower, language, data and regulator expectations often require local procedures.
10. Employment and Labour
10.1 Employment Standards and Workplace Regulation
Employment Framework
The Labour Code, collective bargaining agreements, company agreements, employment contracts and case law regulate employment. Core rules govern working time and leave, remuneration, health and safety, equal treatment and non-discrimination, employee representation and social-security matters. Collective agreements often set more favourable or sector-specific terms.
Companies employing at least 11 employees for 12 consecutive months must establish a social and economic committee, with broader information and consultation rights in companies with at least 50 employees.
An indefinite-term employee may be dismissed only for a real and serious personal or economic cause and after the prescribed process. Personal dismissal normally requires an invitation to a preliminary meeting, the meeting itself, and a reasoned dismissal letter sent after the statutory waiting period. Notice and severance depend on seniority, contract and collective agreement, except in cases of gross misconduct. Protected employees require labour-inspector authorisation.
Economic dismissals are subject to specific requirements, including prior redeployment efforts and employee-representative consultation. Selection criteria must also be applied where several employees within the relevant professional category may be affected. Depending on the number of contemplated redundancies and the employer’s workforce, a job-protection plan (plan de sauvegarde de l’emploi – PSE) and administrative validation or approval may also be required. Claims are heard by employment tribunals. Compensation for dismissal without real and serious cause is subject to the statutory scale, but null dismissals, including discrimination or whistle-blower retaliation, follow separate remedies.
10.2 Executive Compensation and Restrictive Covenants
Compensation and Incentives
Executive packages combine salary, variable compensation, benefits, severance and equity instruments. Corporate officers may not have an employment contract unless they perform genuine separate technical duties under subordination. Listed companies face shareholder votes, disclosure and governance-code constraints. Change-of-control protection must be coordinated with corporate approvals, regulated remuneration rules and tax and social-security treatment.
Equity tools include free shares, stock options, warrants and founders’ warrants, as well as ordinary or preference shares and carried-interest mechanisms. Each has eligibility, vesting, holding, valuation and tax conditions. Good-leaver/bad-leaver terms and repurchase prices must be drafted carefully in light of corporate, employment and tax rules. The 2025–26 tax framework and transaction structure should be confirmed when grants are made and on exit.
A post-termination non-compete covenant is enforceable only if necessary to protect legitimate interests, limited in time and geography, proportionate to the role and accompanied by financial compensation. The applicable collective agreement may impose further conditions. Non-solicitation and confidentiality clauses do not always require compensation, but they must not operate as disguised non-competes. IP, confidentiality, return-of-property and data-access provisions should be reinforced for senior executives.
11. Real Property and Commercial Leasing
11.1 Requirements for Land Ownership
Ownership and Foreign Investors
Real estate may be held directly, jointly, through co-ownership, through a civil real-estate company or another corporate vehicle. Ownership and other rights in rem are evidenced through notarised deeds and registration with the land registry. Long leases, building leases and emphyteutic leases can allocate durable development rights without transferring freehold title.
Foreign individuals and companies can generally acquire, hold and dispose of French real estate without residence or nationality restrictions. They should nevertheless consider legal capacity, certified corporate documents, sanctions and AML checks, tax residence, financing and ownership structure. Agricultural land may be subject to SAFER pre-emption and operational approvals, while strategic assets or an entity conducting sensitive activities can raise foreign-investment issues.
Acquisition taxes, registration duties, VAT and capital-gains taxation depend on the asset, seller, purchaser and structure. Ultimate beneficial owners must be disclosed for acquisition vehicles. Notaries verify title, mortgages and public-law rights and collect applicable taxes. Non-resident ownership does not eliminate French filing, property-tax or representative obligations.
11.2 Commercial Real Estate Transactions
Acquisition and Financing
Commercial real-estate transfers are normally documented by a notarised deed registered with the land registry. Due diligence covers title, easements, security, leases, planning, construction, environmental condition, energy performance, co-ownership, insurance, tax and technical matters. Title insurance is less common than in common-law jurisdictions because notaries and registration verify title, although transactional insurance may cover identified risks.
Environmental diligence is essential for industrial sites. Parties allocate remediation risk contractually, but public-law liability may remain. Financing commonly uses a conventional mortgage or, where available, a lender’s statutory special mortgage, assignments of rents and insurance, account pledges and share security. Registration determines mortgage priority, and enforcement is generally judicial.
Commercial Leases
The statutory commercial-lease regime commonly provides a nine-year term with tenant break rights every three years, subject to exceptions. Tenants generally benefit from renewal rights or an eviction indemnity. Assignment, subletting, service charges, works, indexation, reinstatement and guarantees require careful drafting. Since 28 May 2026, a qualifying commercial tenant without undisputed rent or service-charge arrears may request monthly rent payments. For leases concluded or renewed from 26 May 2026 and eligible for monthly payment, the aggregate security requested by the landlord is capped at one quarter’s rent; statutory deadlines also govern the return of deposits and other security at the end of the lease.
Axipiter
5 rue de Téhéran,
75008 Paris,
France
31 avenue Maréchal de Saxe,
69006 Lyon,
France
(+33) 1 78 96 80 00
erick@axipiter.fr www.axipiter.fr
Trends and Developments
Authors
Axipiter is an independent French business law firm with offices in Paris and Lyon and around 30 lawyers. Its Corporate/M&A team advises companies, founders, management teams, family offices and investment funds on governance, acquisitions and disposals, private equity, venture and growth capital, reorganisations and capital-markets matters. The team regularly coordinates cross-border mandates and supports foreign groups establishing or expanding operations in France, as well as French groups expanding abroad. Axipiter combines this transactional practice with employment, corporate and international tax, customs, commercial litigation, competition, intellectual property, data, public business law, environmental, real estate and construction capabilities. Recent work includes advising shareholders on the sale of a French cybersecurity company to an international industrial group, investors on several health-tech, renewable energy and circular-economy financings, founders on disposals to French and European buyers, and corporate groups on acquisitions, reorganisations and French market-entry projects.
Investing in France in 2026: Turning Regulatory Complexity into Transaction Certainty
A market that remains open, but expects preparation
France continues to combine a large domestic market, a deep pool of technical talent and an active ecosystem of founders, corporates and investors. It also offers international buyers a legal environment that is codified and relatively predictable. The practical challenge is not whether foreign investment is welcomed, but whether the transaction has been prepared early enough across all relevant workstreams.
That distinction matters in 2026. Geopolitical scrutiny, tighter financing conditions, increasing regulation of data and technology, and pressure on sustainability claims have widened the gap between a commercially agreed deal and an executable one. A buyer can preserve speed and negotiating leverage by identifying the issues that affect timetable, price and post-closing integration before exclusivity or signing.
For international acquirers, the most successful French transactions are therefore approached as integrated projects. Corporate structuring remains central, but employment, tax, foreign-investment review, competition, IP, data, environmental and real-estate matters increasingly determine whether the deal closes on time and delivers its expected value.
Foreign direct investment review has become a mainstream deal issue
The French foreign direct investment (FDI) control regime is no longer relevant only to obvious defence assets. Its scope includes critical infrastructure and services, public health, food security, sensitive data and research and development in critical technologies such as artificial intelligence, semiconductors, cybersecurity and biotechnologies. Indirect acquisitions and intra-group changes can be caught, and the analysis follows the full ownership chain.
The latest activity figures illustrate the regime’s importance. The French Treasury’s annual report for 2025, published in September 2026, records 418 filings, compared with 392 in 2024. Of the decisions rendered on authorisation requests, 52% concerned transactions found eligible for review, and 49% of authorised investments were subject to conditions. Formal prohibitions remain rare, but conditions can affect governance, access to information, supply arrangements, intellectual property, strategic capacity and future disposals.
The practical conclusion is not that foreign buyers should avoid sensitive sectors. It is that scope analysis should begin when the target perimeter and investor chain are first known. The parties should determine whether an authorisation or an advance ruling is appropriate, decide who leads engagement with the Treasury, and reflect the process in the long-stop date, conduct covenants and risk allocation.
Where several approvals apply, sequencing is critical. French FDI review may run alongside merger control, sector authorisations, lender approvals and foreign filing processes. The buyer should also anticipate the information required from its ultimate owners and financing sources, as gathering and validating that information can take longer than the legal review itself.
Deal certainty begins before the letter of intent
Competitive processes often encourage short timetables and a narrow initial focus on valuation. In France, early legal structuring can improve the credibility of a bid without making it unnecessarily conditional. A concise regulatory and stakeholder map prepared before the letter of intent can identify the matters that genuinely affect signing or closing.
The applicable merger-control thresholds changed shortly before this Guide was prepared. For notifications made from 1 September 2026, the general French thresholds increased to combined worldwide turnover above EUR250 million and French turnover above EUR80 million for at least two parties. The retail thresholds increased to EUR100 million worldwide and EUR20 million of French retail turnover for at least two parties, while specific overseas thresholds remain. The reform removes some transactions from mandatory review, but parties must still test the EU thresholds, identify the correct turnover perimeter and avoid pre-clearance integration where a filing remains required.
The map should cover, at a minimum:
- merger-control and foreign-investment filings;
- consultation of the social and economic committee and any information rights affecting the process;
- change-of-control provisions in financing, material contracts, public contracts, leases and permits;
- regulated-activity approvals and the portability of authorisations;
- tax structuring, acquisition debt and the availability of security; and
- separation issues where the target is a business line or carve-out rather than a standalone company.
This exercise allows conditions precedent to be limited to matters that are objectively necessary. It also informs the long-stop date and the level of effort each party must undertake to obtain clearance. Vague obligations to use “best efforts” are less useful than a clear allocation of filing responsibility, information co-operation, remedies, appeal strategy and the consequences of conditions imposed by authorities.
The same discipline applies to interim operating covenants. A buyer needs protection against value leakage and unusual conduct between signing and closing, but it must not exercise control prematurely. Clean-team protocols and clear escalation routes help the parties exchange the information needed for planning while respecting competition law, confidentiality and the target’s operational independence.
Pricing mechanisms are doing more work
Where buyers and sellers disagree on outlook, or where financing remains selective, the purchase-price mechanism becomes a tool for allocating uncertainty. Locked-box structures continue to offer simplicity and price visibility when reliable historical accounts and leakage protection are available. Completion accounts are better suited to businesses with volatile working capital, rapidly changing debt or a perimeter that is still being separated.
Earn-outs and other deferred consideration mechanisms can bridge a valuation gap, but they frequently shift disagreement into the post-closing period. The agreement should define the metric, accounting policies, permitted management actions, information rights, dispute process and treatment of acquisitions, disposals and exceptional items. If the seller remains involved, the interaction with employment status, governance and tax treatment must also be addressed.
Warranty and indemnity insurance is increasingly considered in competitive or sponsor-led transactions. It can facilitate a clean exit and provide a buyer with meaningful recourse, but it is not a substitute for diligence. Known issues, forward-looking obligations, transfer pricing, cyber incidents and some regulatory risks may be excluded or require specific underwriting. The timetable should allow the insurer to review the same evidence as the buyer and its advisers.
Governance is part of the investment thesis
Minority and consortium investments require more than a list of veto rights. French SAS companies offer considerable flexibility, but the articles of association and shareholders’ agreement perform different functions. Rights that must bind the company or remain effective against third parties may need to appear in the articles, while commercially sensitive arrangements are often retained in the agreement.
International investors should translate their governance model into operational rules. Board composition, quorum, information flows, delegation of authority and signing policies should work in practice from closing. Reserved matters should protect the investor without paralysing ordinary business, and deadlock mechanisms should distinguish a temporary disagreement from a structural failure of the partnership.
Exit provisions also deserve early attention. Transfer restrictions, tag-along and drag-along rights, liquidity processes and valuation mechanics must fit the expected investment horizon and financing structure. Management incentives should be reviewed simultaneously from corporate, employment and tax perspectives, particularly where leaver provisions or repurchase mechanics can affect both enforceability and economics.
The target’s intangible assets may be its principal assets
For technology, healthcare, consumer and service businesses, legal ownership of intellectual property and data often determines value. A French target may use software created by employees, founders, contractors and open-source communities under different legal rules. Copyright in commissioned work does not automatically vest in the customer, and employee-created IP follows specific regimes depending on the asset.
Buyers should verify chain of title, registration, licences, contractor assignments, open-source compliance and security interests. Trade secrets require evidence of reasonable protective measures, not merely a confidentiality clause. Brand portfolios should be checked against the territories and product categories in the business plan, and change-of-control clauses may affect core technology licences.
Data diligence has become equally important. The buyer should understand which datasets are collected, the lawful basis for processing, retention periods, major incidents, cookie practices and international transfers. A clean data room does not itself make disclosure lawful: personal data should be minimised, redacted or placed behind controlled access, and post-closing migration should have its own legal basis and security plan.
AI creates both value and inherited compliance risk
The EU AI Act moved into an important enforcement phase on 2 August 2026, when the general enforcement framework and new transparency requirements became applicable; its governance rules and obligations for general-purpose AI models had applied since August 2025. High-risk requirements follow the revised timetable. Even where a target is not an AI provider, it may deploy third-party tools in recruitment, customer service, fraud detection, pricing, content generation or product features.
Transaction diligence should therefore begin with an inventory rather than a generic warranty. The buyer needs to know which systems are used, the target’s role in the regulatory chain, what data trained or feeds the system, whether individuals are informed, how outputs are reviewed and which vendors bear contractual responsibility. Undocumented experimentation by business teams can create material exposure even when the target does not describe itself as an AI company.
The acquisition agreement can address identified gaps through remediation covenants, specific indemnities, escrow or conditions where necessary. Post-closing integration should establish an approval process, acceptable-use policy, training and incident escalation. This protects regulatory compliance while allowing useful technology to remain part of the value-creation plan.
Employment planning affects both timetable and integration
Employment law is often treated as a diligence topic when it is also a transaction-management issue. Depending on transaction structure and the target’s workforce, the social and economic committee may need to be informed and consulted before the relevant corporate decision is taken. The sequence must be built into the process without undermining confidentiality or creating inconsistent communications.
Buyers should review employee status, working time, variable compensation, collective agreements, employee representation, health and safety, pending disputes and the treatment of key executives. In a carve-out or business transfer, the application of mandatory automatic transfer rules and the treatment of shared employees require early analysis, as the parties are not free to determine which employees will transfer. Retention measures should be aligned with existing incentive rights and French tax and social-security treatment.
Integration planning should not wait for closing. Changes to reporting lines, policies, benefits, locations, tools and data access may require employee information, consultation or individual consent. A realistic first-100-days plan identifies which measures can be implemented immediately, which require a process and which should be preserved until the buyer understands the local organisation.
Tax developments should be mapped to the deal timetable
The 2027 Finance Bill, presented on 1 October 2026 and still subject to parliamentary debate, is expected to favour overall tax stability for businesses, a higher contribution from very large groups and a continued focus on high earners, rather than a structural overhaul. Recent targeted reforms signal a clear trend toward tightening existing tax planning mechanisms. The following five developments deserve attention before signing:
i) Share rollovers and reinvestment
Crucially for deals, the tax-deferral regime for contributions of shares to a holding company (apport-cession) was tightened for disposals of the contributed shares by the holding company from 21 February 2026: the reinvestment period is now three years, the minimum reinvestment is 70% of proceeds, and the reinvested assets or securities must be kept for five years. Sellers’ rollover and reinvestment plans should therefore be tested early.
ii) Interest deductibility
Interest paid on loans from associated but non-related corporate shareholders can now be deducted up to a market rate, where this is higher than the standard cap, extending a benefit previously limited to related companies. This applies to financial years closing from 31 December 2025. However, the general cap on net financial expenses continues to apply and the market rate must be substantiated.
iii) Pillar Two
The 2026 Finance Act again adjusts the French rules on the global minimum tax for large groups. An acquisition can change the perimeter of a group in scope, so the target’s Pillar Two position and reporting obligations should form part of diligence and integration planning.
iv) Large groups
The exceptional surtax on very large companies was extended for a second year, with the turnover threshold raised to EUR1.5 billion. The 2027 Finance Bill, presented on 1 October 2026, would partially extend it for a third year, at lower rates. This proposal remains subject to amendment during the parliamentary process.
v) Management incentives
Where gains made by executives on their equity are regarded as having been acquired in consideration for their functions, they are taxed as salary by default, with only the portion below a performance-based ceiling potentially taxed as a capital gain if the applicable statutory conditions are satisfied. For securities other than qualifying free shares, stock options and founders’ warrants, those conditions include a holding period of at least two years and a genuine risk of loss. The 2026 Finance Act refined this regime, so sponsors should model manager returns on the current rules and revisit existing plans (see Governance is part of the investment thesis above).
Because tax rules change annually and often apply based on specific closing dates, effective dates must be strictly mapped against the deal timetable. For cross-border transactions, this analysis should also be coordinated with transfer pricing, VAT, customs and the intended post-closing operating model.
Real estate and environmental exposure can change the economics
Owned or leased sites should be reviewed as operational assets, not only legal documents. Title, planning permissions, classified-installation status, soil contamination, energy performance, repair obligations and change-of-control clauses can affect continued operation and future investment. In an asset deal, the transferability of permits and leases may determine the perimeter that can close.
The French commercial-lease framework provides significant tenant protection but also imposes formal rules on duration, renewal and allocation of charges. The Law of 26 May 2026 introduced, among other measures, a tenant right to request monthly rent payments and rules on the release of excess security. Buyers should reflect current cash-flow and guarantee arrangements in their model rather than relying solely on headline rent.
Environmental liabilities require both contractual allocation and an operational plan. An indemnity may protect value between the parties, but it does not prevent regulators from addressing the person liable under public law. Technical evidence, historical use and realistic remediation scenarios are therefore essential when a site is material to the investment thesis.
Dispute-resolution planning should begin before signing
Cross-border investors should anticipate how contractual and post-closing disputes will be handled. Governing-law, jurisdiction and arbitration clauses must be consistent across the transaction documents, particularly where the acquisition agreement, shareholders’ agreement, transitional services and financing arrangements form part of the same transaction.
Warranty and indemnity procedures, limitation periods, evidence-preservation obligations and access to information after closing should be operational rather than merely standard. French courts can provide urgent interim relief, including protective and evidentiary measures, while arbitration can offer procedural flexibility and, where the parties so provide, confidentiality for international transactions.
Early co-ordination between the transactional and litigation teams can materially improve the enforceability of negotiated protections. Identified disputes should be reflected in pricing, specific indemnities or escrow arrangements, and the transaction documents should clearly allocate control of third-party claims and settlement decisions.
A practical route to a more certain closing
International investors can make a French acquisition materially more predictable by organising the transaction around a few decisions:
- establish the regulatory and employee-process map before committing to the timetable;
- align price mechanics with the quality of financial information and the source of uncertainty;
- document governance as an operating system, not simply a set of protections;
- treat IP, data and AI as assets with provenance, dependencies and compliance costs;
- design acquisition financing, tax structure and post-closing flows together;
- translate diligence findings into specific closing, pricing or integration actions; and
- assign owners and deadlines for the first 100 days before funds are transferred.
France remains an attractive and navigable jurisdiction for cross-border investment. The legal framework rewards buyers that prepare early, distinguish true execution risks from manageable compliance matters, and coordinate specialist workstreams around a single transaction strategy. In that setting, regulation becomes less an obstacle than a method for creating deal certainty and protecting value after closing.
Axipiter
5 rue de Téhéran,
75008 Paris,
France
31 avenue Maréchal de Saxe,
69006 Lyon,
France
(+33) 1 78 96 80 00
erick@axipiter.fr www.axipiter.fr
Law and Practice
Authors
Axipiter is an independent French business law firm with offices in Paris and Lyon and around 30 lawyers. Its Corporate/M&A team advises companies, founders, management teams, family offices and investment funds on governance, acquisitions and disposals, private equity, venture and growth capital, reorganisations and capital-markets matters. The team regularly coordinates cross-border mandates and supports foreign groups establishing or expanding operations in France, as well as French groups expanding abroad. Axipiter combines this transactional practice with employment, corporate and international tax, customs, commercial litigation, competition, intellectual property, data, public business law, environmental, real estate and construction capabilities. Recent work includes advising shareholders on the sale of a French cybersecurity company to an international industrial group, investors on several health-tech, renewable energy and circular-economy financings, founders on disposals to French and European buyers, and corporate groups on acquisitions, reorganisations and French market-entry projects.
Trends and Developments
Authors
Axipiter is an independent French business law firm with offices in Paris and Lyon and around 30 lawyers. Its Corporate/M&A team advises companies, founders, management teams, family offices and investment funds on governance, acquisitions and disposals, private equity, venture and growth capital, reorganisations and capital-markets matters. The team regularly coordinates cross-border mandates and supports foreign groups establishing or expanding operations in France, as well as French groups expanding abroad. Axipiter combines this transactional practice with employment, corporate and international tax, customs, commercial litigation, competition, intellectual property, data, public business law, environmental, real estate and construction capabilities. Recent work includes advising shareholders on the sale of a French cybersecurity company to an international industrial group, investors on several health-tech, renewable energy and circular-economy financings, founders on disposals to French and European buyers, and corporate groups on acquisitions, reorganisations and French market-entry projects.
